
Tudor Gold Corp
TUDTudor Gold Corp., a junior resource exploration company, engages in the acquisition, exploration, and development of mineral properties in Canada. The company primarily explores for gold, copper, silver, precious, and other base metals. The Company's flagship project is the Treaty Creek property covering an area of approximately 17,130 hectares located in the Golden Triangle area to the north of Stewart, British Columbia, Canada. It also holds a 100% interest in the Crown project and the Eskay North project, which are located in the Golden Triangle area. Tudor Gold Corp. is headquartered in Vancouver, Canada.
Score
—Data Quality
Market Cap
N/A
Total valuation
Stock Price
N/A
Latest close
Free Cash Flow
N/A
Annual
Financial Position
N/A
Cash position
PEG Ratio
ⓘN/A
P/E ÷ growth
Analysis
Subscribe to see the AI Analysis
Score breakdown, criteria, red flags, bull/base/bear scenarios.
SubscribeFinancials
Asset Pipeline
Subscribe to see the Asset Pipeline
Jurisdiction exposure, project portfolio, cost structure.
SubscribeInformation
Key Information
Legal Entity
Tudor Gold Corp
Sector
Precious Metal
Founded
June 14, 2016
Employees
2
Reporting Currency
CAD
Contact Phone
604 559 8092
Website
www.tudor-gold.comHeadquarters Address
999 West Hastings Street , Vancouver , BC V6C 2W2 , CA
Identifiers
ISIN
CA89901T1093Commodity Portfolio
Stock Exchanges
Organization
Chart
Interactive chart powered by TradingView. Use the chart tools to analyze price trends.
Videos

White Gold ($WGO | $WHGOF) Advances Its 3-Million-Ounce Gold Resource in Yukon
Key Highlights
brief- Don Durrett flags Tudor Gold as a 25-million-ounce peer whose development timeline will be long, drawing a contrast with White Gold's nearer-term production.
White Gold's maiden PEA on 2 of its 3 million ounces delivers C$1.9B NPV at $3,600 gold, scaling to C$3B at $4,500. Sub-$1,500 AISC and 225,000 oz/year in the first 5 years make Golden Saddle Yukon's highest-grade development story. The company's largest-ever exploration program is drilling now, targeting district-scale growth across 750,000 acres. Agnico Eagle's 19% stake plus its position in neighboring Talamore/Coffee hints at district-scale consolidation in Yukon. Macro view: a seasonal September/October correction is likely before gold pushes to $5,000, with miners now outperforming the metal.
Rick Rule: Copper Has WAY More Potential Than Gold
Key Highlights
brief- Rick raises the Tudor Gold litigation only in the context of Seabridge's sale process, arguing that at current gold prices the buyer can let that dispute play out rather than resolving it pre-close.
Major copper producers need roughly $250 billion just to hold production steady — and they don't have the capital, opening a financing boom for streamers. Wheaton Precious and Franco-Nevada could be the biggest winners — silver byproducts from copper mines earn much higher multiples inside a streamer. Rule is rotating out of Franco, Wheaton, and Agnico into smaller, more speculative juniors to front-run the coming M&A wave. Most majors face a five-year depletion problem — only Agnico and Goldfield, Rule says, have near-term production covered. A red flag in royalty M&A: rapid capital deployment without a structural edge usually signals overpayment, not bargain hunting.
Teuton Resources Stock Paying Dividends in Shares
Key Highlights
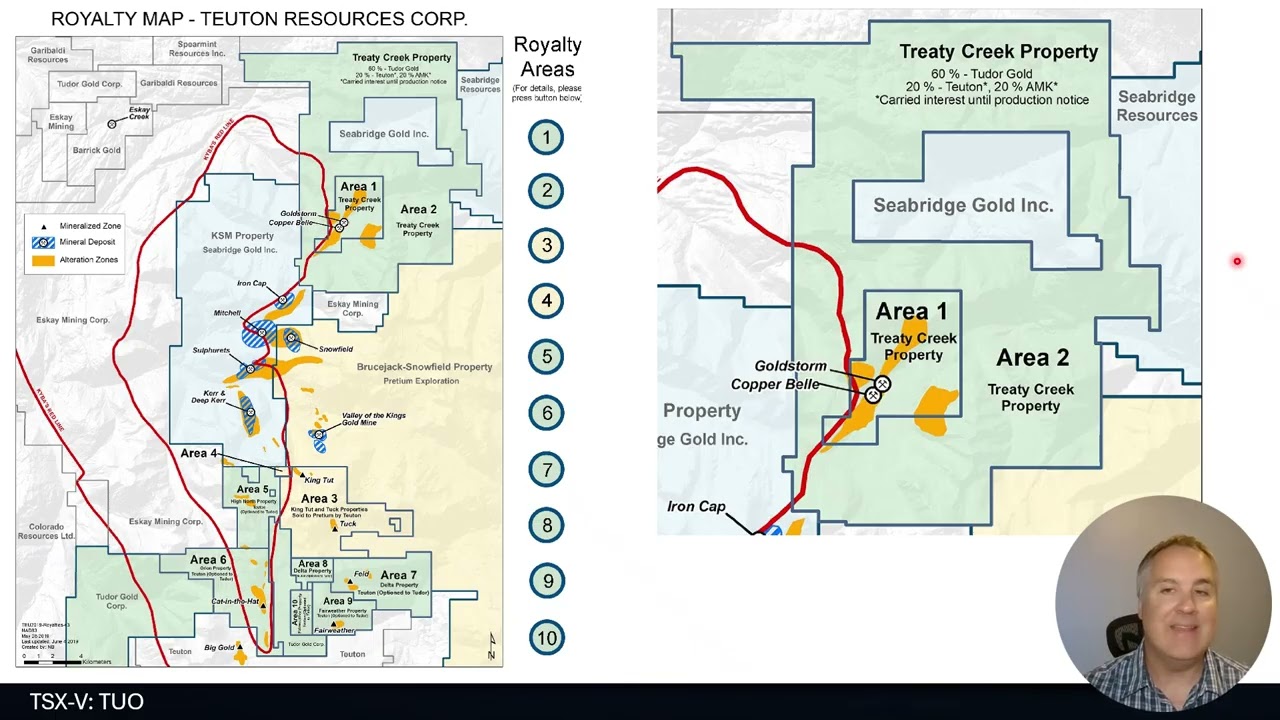
detailed- Tudor Gold owns 80% of Treaty Creek and, because of Teuton's free carry, funds all expenditures on the Goldstorm deposit up to a production decision.
- The presenter notes Tudor Gold's current management previously put the high-grade Brucejack underground gold mine in the Golden Triangle into production.
- The presenter argues the proposed spinout that isolates Treaty Creek in the parent company would make it easier for Tudor Gold to buy out Teuton's remaining 20% stake.
Teuton Resources owns a 20% stake plus a 0.98% NSR (net smelter return — a royalty on production revenue) in Goldstorm, a 29-million-ounce gold deposit. A free carry means partner Tudor Gold funds all Treaty Creek spending until a production decision, so Teuton grows its flagship without dilution. A proposed double spinout gives shareholders free shares in two new companies holding the royalty and property portfolio, with Treaty Creek kept in the parent. The host argues the current price and roughly $130 million market cap do not reflect the value and potential of Teuton's asset portfolio. The Golden Triangle's scale anchors the case: Seabridge Gold's KSM project nearby hosts 180 million ounces, the world's biggest undeveloped gold project.

Live Q&A with Rick Rule, Rudi Fronk, and Steve Barton
Key Highlights
detailed- Tudor's objections to the roughly 22 km haulage tunnel, about 12.5 km of which crosses Tudor's ground, are holding up the M2-4-5 permit amendment Seabridge needs, and the statutory decision-maker wants the dispute settled before granting it.
- Tudor sued the province in BC Supreme Court claiming it lacked authority to grant Seabridge's tunnel rights; the province's response says those approvals were in place well before Tudor arrived in 2016, that Tudor failed its own due diligence, and that the claim is time-barred under Canada's two-year Limitations Act.
- Fronk's stated route out is a negotiated tunnel realignment rather than a payout: Seabridge can flex the tunnel around Tudor's pit shell but cannot commit until Tudor publishes a mine plan, and he says a PEA-level plan would be enough to start negotiating.
- On a takeover he argues Tudor's ore is largely refractory and does not fit Seabridge's flowsheet, so routing material through the tunnel would need a plant redesign plus a major environmental assessment amendment for roasting or oxidation.
Seabridge's KSM is now the world's largest undeveloped gold project by reserves and resources, and second-largest for copper. Fronk argues capital efficiency is the real draw: at current metal prices after-tax NPV reaches $35 billion against a $6.4 billion build. Over $1 billion of roads, camps and grid tie-in is already built, so an incoming partner inherits spending rather than starting from zero. The remaining risk is a tunnel dispute with Tudor; both sides want a negotiated fix because neither wants a court trial. Nearly half of $750 million in on-site construction spending already flows to First Nations companies under impact benefit agreements.

Live Q&A with Rick Rule, hosted by Steve Barton
Key Highlights
brief- Rule says it is highly likely Tudor's legal action is holding up the Seabridge joint venture.
- He expects no announcement before the dispute sees settlement or adjudication.
Rule argues resource equities are not excessive despite two years of gains, but liquidity-crisis risk means checking your own exposure. Mining consolidation looks set to continue; Rule favors owning likely takeover beneficiaries because mergers cut overhead and lower capital costs. Rule calls Cameco's flood-driven sell-off a buying opportunity, since a three-month outage barely dents reserves measured in decades. Build NPV (net present value — discounted future cash flow) from measured and indicated resources only, then add back optionality for growth and tail. Development-stage mining assets deserve a basket approach across several names, Rule says, never a single speculative position.
Articles
No articles available
Published articles for this company will appear here
Want the full picture on more companies?
Be one of the first.
A room for resource investors taking shape now — independent, spam-free, no hype.