
Falco Resources Ltd
FPCFalco Resources Ltd. engages in the exploration, development, and evaluation of mineral properties in Canada. It explores for base and precious metals, such as gold, zinc, copper, and silver deposits. The company owns mining claims and contractual rights in relation to mining concessions covering approximately 70,000 hectares of land in the Rouyn-Noranda mining camp located in the Province of Québec. Its principal asset is the Horne 5 Project located in the former Horne mine. The company was formerly known as Falco Pacific Resource Group Inc. and changed its name to Falco Resources Ltd. in July 2014. Falco Resources Ltd. was incorporated in 2010 and is headquartered in Montreal, Canada.
Score
—Data Quality
Market Cap
N/A
Total valuation
Stock Price
N/A
Latest close
Free Cash Flow
N/A
Annual
Financial Position
N/A
Cash position
PEG Ratio
ⓘN/A
P/E ÷ growth
Analysis
Subscribe to see the AI Analysis
Score breakdown, criteria, red flags, bull/base/bear scenarios.
SubscribeFinancials
Asset Pipeline
Subscribe to see the Asset Pipeline
Jurisdiction exposure, project portfolio, cost structure.
SubscribeInformation
Key Information
Legal Entity
Falco Resources Ltd
Sector
Precious Metal
Founded
August 14, 2014
Employees
502
Reporting Currency
CAD
Contact Phone
514 905 3162
Website
www.falcores.comHeadquarters Address
1100, avenue des Canadiens-de-MontrEal , Montreal , QC H3B 2S2 , CA
Identifiers
ISIN
CA30606C1086Commodity Portfolio
Stock Exchanges
Organization
Chart
Interactive chart powered by TradingView. Use the chart tools to analyze price trends.
Videos

$68M for a Broken Mine. Now It’s a Copper Giant | Firefly Metals Green Bay PEA
Key Highlights
brief- Used as the cautionary comparable: Horne 5 at Rouyn-Miranda has a June feasibility with a $3.4B after-tax NPV, but an EV of just $210M (0.06x NAV) while it waits on a Quebec ministerial decree.
- Needs ~$1.8B of construction capital against a C$180M market cap — the host argues a large NPV is worthless without a credible funding path.
Firefly's Green Bay PEA values the A$68M mine at A$2.2B — a 32x paper markup built on hydro power, brownfield infrastructure, and top-decile copper grades. Base case: 50,000 tonnes copper-equivalent yearly for 14 years; C1 cash costs (a mine's site-level operating cost) hit US$2.05/lb thanks to hydropower. The 32-year mine plan frontloads 77% measured-and-indicated ore, but 20% still sits in inferred — a real long-life mining risk if drilling disappoints. Sustaining capital adds A$876M to Firefly's A$513M initial capex, lifting life-of-mine capital to A$1.4B — almost double the headline figure. Compared to peers, Firefly screens mid-pack: cheaper than New Found Gold on EV/NAV (enterprise value to project net asset value), pricier than Falco Resources.

Falco Resources Reprices a World-Class Gold Asset in Quebec
Key Highlights
detailed- The guest says the feasibility study update announced the week before the June 2026 interview puts the project's after-tax NPV5 at about C$3.35 billion on a US$3,600/oz gold base case, a 244% increase over the 2021 study, with an after-tax IRR near 28.2% and about C$6.4 billion of after-tax life-of-mine cash flow; at US$4,500/oz he cites an after-tax NPV5 of about C$5.1 billion with an IRR near 37%.
- He attributes the jump to refreshing years of capex and opex escalation and to a much stronger long-term gold price than the US$1,600/oz assumption behind the 2021 study.
- Initial development capital is put at about C$1.75 billion for a polymetallic deposit with 5.2 million ounces of gold-equivalent reserves and close to 9 million ounces of gold-equivalent resources across 80 million tonnes of ore.
- Silver and copper by-product credits are said to hold all-in sustaining cost below US$800/oz, which the guest argues would place the asset in the first quartile of gold-sector low-cost production, on a 16,000 tonne-per-day plan producing over 220,000 payable ounces a year, roughly 300,000 ounces on a gold-equivalent basis.
- Permitting is framed as the next gate, with the host citing Quebec's Ministry of the Environment as indicating the review is entering its final stretch, while the guest expects the environmental analysis to be completed by autumn 2026 and a decision by decree before the end of 2026, ahead of filing the study and starting dewatering and financing work.
Falco's refreshed Horne 5 study lifts after-tax NPV to C$3.35 billion at US$3,600/oz gold, a 244% jump on the 2021 study. Lessard attributes the jump to a reset price deck plus years of capex and operating cost escalation since the 2021 study. AISC (All-In Sustaining Cost — what it really costs to produce an ounce) sits below US$800/oz, aided by silver and copper credits. Permitting is the near-term gate: environmental analysis due by autumn 2026, with a government decree possible before year-end. Financing talks, detailed engineering and initial dewatering run in parallel over the next 6-12 months on roughly C$1.75 billion of initial capex.
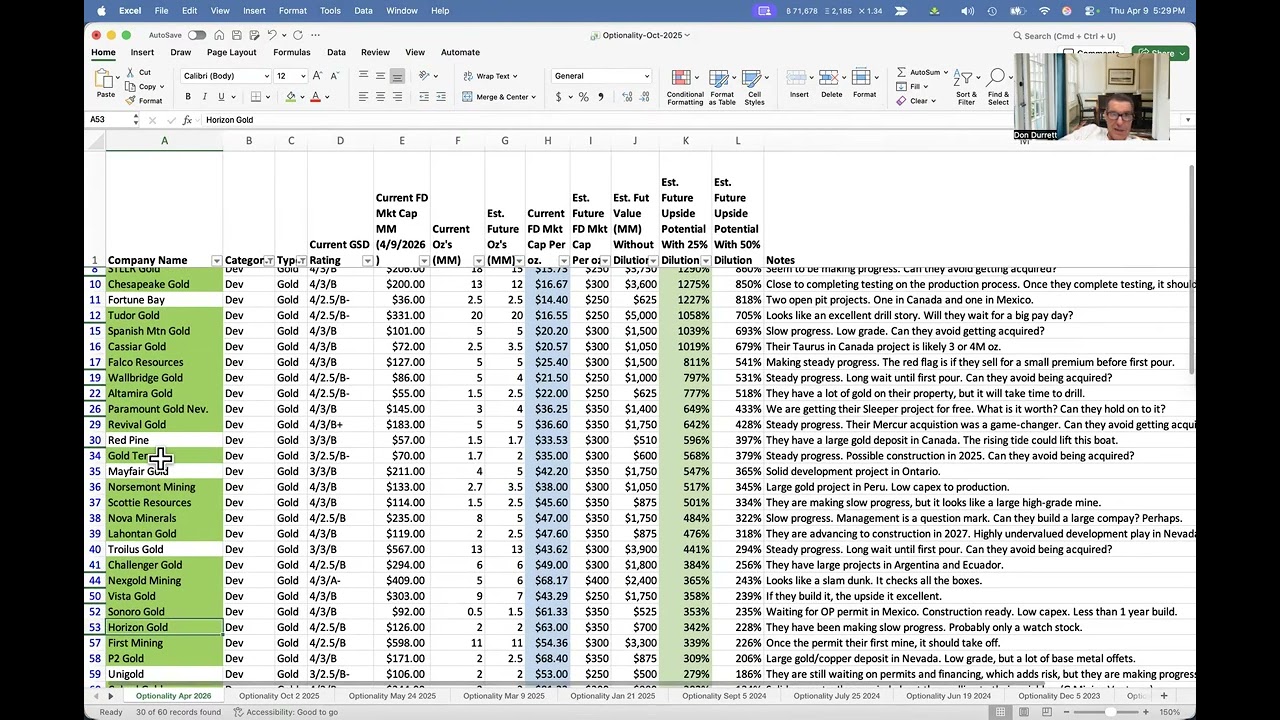
Optionality Update - April 2026
Key Highlights
detailed- Durrett calls Falco Resources' valuation absolutely insane: a $127 million market cap for 5 million ounces works out to about $25 per ounce in the ground.
- He says at deal prices of $300 per ounce the stock becomes an eight-bagger on optionality alone if it sells, and even better if it builds the mine.
G Mining Ventures' $2 billion acquisition of G2 Goldfields implies roughly $500 per ounce, resetting valuation benchmarks for Canadian gold developers. A 72% premium for an exploration-stage project lifts per-ounce benchmarks, creating optionality across junior gold and silver names. Durrett screens about 60 juniors by future ounces against market cap, applying $250-$450 gold and $5 silver in-ground price assumptions. Names like Freegold, Triumph, Falco and Cabral show multi-bagger optionality if further deals clear at $300-$450 an ounce. He expects development-stage stocks to re-rate together if upcoming acquisitions keep pricing gold in the ground near $400 per ounce.
Articles
No articles available
Published articles for this company will appear here
Want the full picture on more companies?
Be one of the first.
A room for resource investors taking shape now — independent, spam-free, no hype.