Denarius Metals Corp
DNRSFDenarius Metals Corp. is a Canadian junior company, which engages in the exploration, development, and eventual operation of polymetallic mining projects. It focuses on the Lomero Project in Spain. The company was founded on March 31, 1992 and is headquartered in Toronto, Canada.
Score
—Data Quality
Market Cap
N/A
Total valuation
Stock Price
N/A
Latest close
Free Cash Flow
N/A
Annual
Financial Position
N/A
Cash position
PEG Ratio
ⓘN/A
P/E ÷ growth
Analysis
Subscribe to see the AI Analysis
Score breakdown, criteria, red flags, bull/base/bear scenarios.
SubscribeFinancials
Asset Pipeline
Subscribe to see the Asset Pipeline
Jurisdiction exposure, project portfolio, cost structure.
SubscribeInformation
Key Information
Legal Entity
Denarius Metals Corp
Sector
Precious Metal
Founded
July 20, 2021
Employees
78
Reporting Currency
USD
Contact Phone
416-360-4653
Website
www.danakali.comHeadquarters Address
401 Bay Street , Toronto , ON M5H 2Y4 , CA
Identifiers
ISIN
CA2482332079CUSIP
23637W105
Commodity Portfolio
Stock Exchanges
Organization
Chart
Interactive chart powered by TradingView. Use the chart tools to analyze price trends.
Videos

Beaver Creek 2026 - Best Stocks
Key Highlights
detailed- Durrett says the fourth quarter is the make-or-break milestone for Denarius and that the mill build has slipped slightly.
- Ramping now looks like the first quarter of next year rather than the fourth quarter, on a 1,500 tonne per day mill he does not expect to fill for two years.
- He argues the Zancudo project alone is worth the company's market capitalization of about $230, and that the Lomero project in Spain adds a solid gold-equivalent asset.
- He expects a Toronto listing next year, which he says would bring the company into Canadian ETFs where it is currently absent, and he notes strong insider ownership.
Gold at $4,100 anchors his buy-the-dip plan: add again below $4,000, and again below $3,700. His Beaver Creek list holds 37 stocks, all rated as tenbaggers (ten-times-plus targets), with seven winners out of ten as the goal. He grades risk-reward by letter and number; near-term producers screen best, while late-stage projects carry more risk. Discovery Silver and Osisko Gold Group lead his Canadian gold picks, and Silver X's 250 million ounce resource lifted the grade. Low insider ownership makes Andean Silver, Talisker and Avino the likeliest takeover targets on his list.
Denarius Metals: Concentrate Sales Targeted for Early 2027 at Zancudo
Key Highlights
detailed- Concentrate sales at Zancudo are targeted for early 2027; moving from crushed-rock shipments to concentrate with Trafigura should lift gold payability from about 65% to 90%
- Full-year 2025 guidance of 7,000-10,000 oz payable gold at 35-40% margins, with 2026 expected at 25,000-30,000 oz; the 2028 target is 45,000-50,000 oz/year once the project hits 1,000 tpd
- Spain pipeline includes a 22% JV in Agua Blanca (5,000 tpd plant restart targeted mid-2027), 100%-owned Lamero (about two years to production), and Torral (about three years out)
- Trafigura is a 15% shareholder (after the August private placement), the 7-year offtake counterparty, and a $16M prepayment lender ($9M already drawn, $7M additional to be drawn in the second half of the year)
- Current Zancudo resource is about 1.2M oz gold equivalent with a 15,000-meter drill program underway; a resource update incorporating drill results is expected in spring 2027
Denarius targets commercial concentrate production at Zancudo by early 2027, with plant installation underway and Q3 output tracking 50% above Q2. CFO Mike Davies projects 7,000-10,000 payable ounces of gold this year and 25,000-30,000 next year, with current margins running 35-40%. Trafigura is both a seven-year offtake partner and roughly 15% shareholder, after stepping up via an August placement that funded Denarius's stake in Copper Giant. Gold payability should jump from about 65% on crushed rock to 90% once concentrate shipments start, lifting gold to ~95% of Zancudo revenue. In Spain, a 22% JV in the permitted Aguablanca plant is targeted to restart by mid-2027, with 100%-owned Lomero about two years behind it.

Summit Royalties – Comprehensive Update On 4 Producing and 3 Key Development Assets
Key Highlights
detailed- Clark says Zancudo production rose 67% over Q1 from the direct shipping ore operation, with last quarter's head grade around 10 g/t gold and about 300 g/t silver.
- The main growth driver is a 1,000 tonne per day plant that Clark says is turning on soon and could lift the mine to 50,000+ gold-equivalent ounces per year.
- Summit holds only a 0.5% royalty on Zancudo, so it is a small part of Summit's economics today, but Clark is watching the mill build and the strong drill results closely.
- Clark notes Denarius is already making money at the small direct shipping operation before the plant is even in place.
Drew Clark argues Summit Royalties trades at 0.75x net asset value (NAV) against 1.2-1.6x for royalty peers, leaving room to re-rate. Four producing royalties are compounding as operators expand — Madsen, Bomboré, Zancudo and Keysbrook grow Summit's cash flow at no extra cost. Copperstone and Pitangu should reach production in 2027, with the guest's math valuing the 4% Copperstone gold stream at about US$6 million yearly. Banyan Gold's year-end AurMac PEA (preliminary economic assessment — an early-stage mine study) could re-rate Summit's unvalued royalty on the project. A US$50 million National Bank credit facility funds accretive royalty acquisitions without heavy dilution, and management owns 12% of the company.

Eastport Critical Metals ($EVI.V | $EVIIF): Targeting a Large-Scale Copper Opportunity in Botswana
Key Highlights
brief- The hosts say Denarius has substantial upside from its US$0.44 share price as of the video date.
- Don characterizes Denarius as a hybrid polymetallic and gold miner because of its Spanish polymetallic asset and Zancudo mine.
Eastport's flagship Matsitama spans 1,854 square kilometres, with a 30-kilometre copper soil anomaly guiding geophysics and initial drilling. Semarule's first assay returned 330 metres of continuous rare-earth mineralization, while a central anomaly hole remains pending. Management prioritizes copper while advancing early-stage nickel, uranium, and rare-earth targets, using portfolio flexibility to allocate limited exploration capital. Botswana offers year-round access, established infrastructure, relatively straightforward permitting, and mining laws rooted in English law, according to Major. Major says Eastport holds $2.5 million cash and plans about 5,000 metres across projects, including 2,000 metres at Matsitama.
Frank Giustra: This Is a Forever War. Own Gold and Copper
Key Highlights
brief- Giustra says that he and Denarius together own about 30% of Copper Giant and have agreed to lock up their shares to see the project through.
Frank Giustra argues a forever war with Iran plus a NATO-Russia standoff keeps energy costly, feeding inflation, currency debasement, and gold demand. Sanctions on Russian reserves pushed China and the BRICS toward a parallel, gold-backed settlement system he expects to entrench gold in monetary architecture. Copper faces a supply shock from decades of underinvestment and falling grades just as AI, defense, and grid demand rise, so prices must go higher. His junior screen is size, grade, location, and politics: buy early and large, then hold, because majors must acquire scarce quality copper deposits. With US debt beyond repair, he holds hard assets: locked-up shares in Copper Giant and Aris Mining's high-grade Segovia gold operation.

Skyline Builders Group ($KAZR): Developing a Large-Scale Tungsten Project in Kazakhstan
Key Highlights
detailed- Don flags that Denarius is building a 1,000-ton-per-day mill, having previously been toll milling, and that the mill is expected to be done before Q4 (2026) begins — a milestone he calls a 'big game changer'.
- John argues Denarius's new Colombian president has a personal relationship with management, which he views as a meaningfully positive signal for permitting given Colombia's rising status as a mining jurisdiction.
- Don notes Denarius has a joint venture with the Saudis, and reports that when chairman Serafino met with a Saudi royal family about gold and copper, the first question they asked was what he had in tungsten — a story he uses to illustrate surging Gulf-state interest in critical minerals.
Skyline Builders Group (KAZR) plans a 50+ year tungsten mine in Kazakhstan targeting 2030 production, with backing from US EXIM and DFC. The project targets 12,000 metric tons of tungsten annually — roughly 15% of current global supply — at cash costs under $100 per MTU. China, Russia, and North Korea control about 87% of global tungsten, creating structural demand for non-Chinese sources used in defense and semiconductors. Management expects US offtake agreements and debt to cover the ~$1.1 billion capex without shareholder dilution, with an MOU already in place. Rotterdam tungsten prices trade at a premium to Chinese prices, signaling Chinese export restrictions rather than a balanced soft market.

SILVER Stocks Set to Go Berserk - 'These Companies Are Printing Cash': John Feneck
Key Highlights
detailed- Speaker calls DNRSF one of the most mispriced gold stocks in the development/exploration category; the late-July share issuance to eliminate debt (which pushed the stock to $0.295) was about 50% absorbed by holders like chairman Serafino Iacono and Aris Mining who are not selling.
- Trading at $0.455 entering the interview versus a year-end target of $0.60; speaker sees ~$0.29-$0.30 as downside support.
- Producing in Colombia and expected to begin production in Spain by Q1 2027; revenue plan rises from under $2M last year to about $20M this year, with 2027 framed as the breakout year.
- Characterized as a growth stock at a value price; Don Durrett has it among his top 25 gold picks.
Silver producers with AISC around $30 are minting cash at $70 silver, says Feneck — he sees $100/oz by next year. Treasury buybacks announced August 19 plus weak US jobs data triggered a sharp precious-metals rally through August. Feneck highlights Pan American Silver, Excellon Resources, Denarius Metals, Goldgroup, iMetal, Spartan Metals, and ANKOR Resources as top names. He expects a 15–20% S&P correction by Q1 2027 and recommends keeping 8–10% cash on hand for drawdowns. Investors should remember mining stocks typically fall with the broader market, even when individual company fundamentals are strong.
What’s Next for Gold & Silver? Market Analysis With Don Durrett and John Feneck
Key Highlights
detailed- The guest calls Q4 'make or break' for Denarius — the new Zancudo mill comes online then, and if it works the company is 'a whole different company' by February with cash to fund Lamero.
- He flags a Colombia tailwind: the new president is publicly pro-mining, and Denarius bought 15.6% of a Colombian copper miner, which moved the stock from 30¢ to 42¢.
- He frames Denarius as his favorite spec bet among small producers but says it 'won't be a spec bet for much longer' once Zancudo hits nameplate.
- He notes the current setup is toll milling at Zancudo while the new mill is being built next door.
Don and John call the Aug 19 gold-silver rally seasonal, not yet a structural breakout; HUI is above 800. Bessent's surprise long-end Treasury bid weakened the dollar and sent GDX up 8% and silver up 10%. Miners are starting to outperform the metal — a leading signal that institutional rotation into the sector could be starting. Undervalued producers with growth ahead — Goldgroup, Excellon, Denarius, LaHontan, 1911 Gold — screen as the best risk-reward in this tape. Both analysts are bullish into Q4 2026 and 2027, but the real test is whether capital rotates from equities into miners.
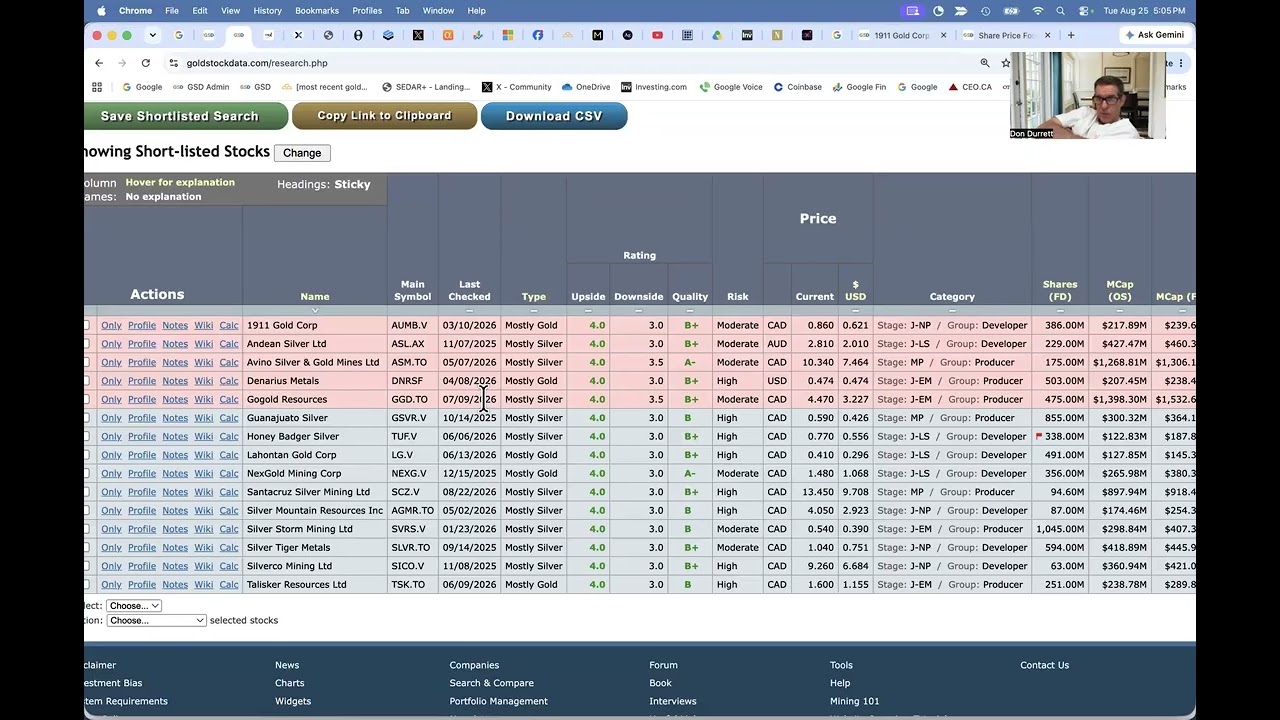
Gold/Silver Miners: Low Hanging Fruit (August 2026)
Key Highlights
detailed- He calls the Q4 of recording 'make or break' — the Colombia mill for Zancudo is being built and the deposit needs to deliver the modeled ~8 g/t to validate the story.
- Zancudo is already ~1M oz and he expects it to double or triple via exploration; that single project underwrites the valuation.
- Beyond Zancudo, four projects are in the pipeline with Lomero (>$200M already invested) coming next.
- The company is OTC-only at the time of the recording; he expects a Toronto listing in Q3 to unlock ETF inclusion.
Don Durrett's 15 low-hanging-fruit names share a single thesis — execution on planned growth at $200 silver and $7,000 gold unlocks 5-20x upside across the list. Junior miners with low insider ownership become prime hostile takeover targets once their assets are de-risked, so a defensive merger often precedes the rerate. The market is still leaving the second-mine pipeline at NexGold and GoGold free, because the first project's standalone value already exceeds today's market cap. Canada's scarcity of new single-asset gold producers gives each one a permanent jurisdiction premium that U.S. peers cannot replicate. AISC (All-In Sustaining Cost — what it really costs to produce an ounce) is the single variable that decides whether each near-term producer on this list rerates or fades.

'There's No Deposits Anywhere' - Why $7 Copper is Only the Beginning: Ian Harris
Copper supply cannot respond to today's record prices because new mines take roughly twenty years from discovery to first pour. Most large near-surface copper deposits are already found, so any future supply will come from deeper, slower projects. Aging US power grids, AI data centers, and EVs create a triple copper demand effect spanning generation, transmission, and end use. Copper Giant's Mocoa project gained a strategic ally when Trafigura signed an off-take deal before the PEA was even published. Colombia's new pro-mining president plus $47 million in treasury let Copper Giant accelerate Mocoa toward a year-end PEA.
Goldgroup Mining ($GORO): Building a Multi-Asset Gold and Silver Producer
Key Highlights
detailed- TOP: Closed the July debenture news on the last day of the month, which initially took the stock to US$0.29; it has since recovered to US$0.43 (as of the interview) after the company announced a 15.6% stake in a major copper project in Colombia.
- Picked up 15.6% of a copper-focused company with 1.1 billion tons of copper in Colombia, where CEO Serafino Iacono has decades of relationships and access.
- Don likes the high-grade Zancudo mine (about 8 g/t, similar to Aris Mining) plus the additional Spain and Udo assets on a risk-reward basis.
- The dilution used to retire debt upset some shareholders, but Don sees it as constructive given the underlying asset quality.
Goldgroup's $15M acquisition of Gold Resource Corp added the Don David silver-gold mine, transforming a single-asset producer into a multi-asset Mexican platform. A 26,000-meter drill program at San Francisco targets resource expansion; restart capital is roughly $25M with a target output of about 50,000 ounces a year. Goldgroup is advancing the Back 40 copper-gold project in Michigan but cites an 18-month permitting risk in a Democratic-leaning state. Eric Sprott, Cala, and other insiders control roughly 70% of the float, sharply limiting the risk of a lowball takeover. Forced Russell 2000 selling after a 15-day inclusion window wiped out half the market cap — a mechanical dip that disciplined investors exploited.

Ian Harris: The Smart Money Is Rushing To Copper
Key Highlights
detailed- Took a roughly 15% stake in Copper Giant through participation in the $31 million financing, with shares locked up for two years.
- Combined with Frank Giustra's position, Denarius and Giustra account for roughly 30% of Copper Giant (about 33-34% with Ian Harris, on an undiluted basis).
- Denarius CEO Serafino Iacono is described in the interview as 'very experienced in Colombia,' with prior success putting projects into production there — providing Colombia operating know-how to Copper Giant.
Colombia's August 7 election of right-wing, business-friendly president Espriella opens a four-year political window for mining in a region long underexplored. Copper Giant closed a $31 million financing the same day Trafigura signed a 10-year, 20% offtake for Mocoa copper and molybdenum at market prices. Trafigura's deal leaves 80% of Mocoa's future production open for further offtakes and is structured to support non-dilutive debt financing at construction. Core shareholders Frank Giustra, Denarius Metals' Serafino Iacono, and CEO Ian Harris locked up stakes for two years, totaling roughly 33-34% on an undiluted basis. Copper Giant expects its Mocoa preliminary economic assessment (PEA) inside 2026 and aims to push the project into construction during the new political cycle.
“There Is Going To Be A Problem” - Metal Shortage Could Last Decades | Ian Harris
Key Highlights
brief- Denarius Metals participated in Copper Giant's just-closed $31 million financing alongside Trafigura, which took a 20% offtake for 10 years at market on the project.
- Ian Harris frames the Denarius/Trafigura deal as a strategic-partner signal that validates Copper Giant's Colombia asset.
Copper faces a structural deposit problem — finding and permitting new mines can take 20+ years from discovery to production. Demand drivers stack up: electrification, EVs, AI data centers, and digitalization all pull on the same constrained supply. Copper now behaves like a strategic resource, with governments and majors scrambling to secure supply ahead of projected shortfalls. Copper Giant closed a $31M financing with a Trafigura-linked offtake, giving it a two-year runway to a construction decision. A pro-mining president takes office in Colombia the same day, removing the project's biggest perceived jurisdictional risk.

Gold & Silver Miners, Macro Risks, and Investing Strategy | Don Durrett and John Feneck
Key Highlights
detailed- Don describes Denarius as an undervalued producer currently at ~20,000 oz/year, ramping to ~40,000 oz by year-end with potential to reach 50,000+ oz next year.
- John highlights the Romero project in Spain — bought from Lundin for $20M Canadian five years ago and now valued at ~$325M Canadian replacement cost — as the standout asset few investors are pricing in.
- Q3 and Q4 are flagged as critical catalysts as Denarius builds a new mill that can support growth into next year, followed by Romero.
- Insider ownership is described as strong, and management is not expected to give the company away at current prices.
- John ranks Denarius as one of his top-10 stocks and says the Spain site visit 'blew my mind'.
Don Durrett calls junior gold and silver miners a once-in-a-generation asymmetric trade — entry prices vanish once gold crosses $5,500–$6,000. He values juniors on a 36-month forward gold/silver price ($7,000 and $200 today) instead of spot, capturing leverage before the metal moves. Build a portfolio pyramid — ETFs and majors form the foundation, junior miners sit on top with capped position sizes near 1% of capital. When the original thesis survives a 40% drawdown, add to the position — averaging down improves blended cost basis and removes emotion. The macro case rests on Fed intervention history from Greenspan through today and ongoing de-dollarization — both push investors into gold.
Silver47 Exploration ($AGA | $AAGAF) on Red Mountain's Critical Mineral Potential & Path to 2027 PEA
Key Highlights
detailed- John argues Denarius is undervalued and led by Serafino Iacono, a 40-year mining veteran who co-founded ARIS
- John says Denarius's Colombia mill should be completed in Q3 2025, with ramp-up through Q4 2025 and Q1 2026
- John claims Denarius's Spanish project, bought for $20M five years ago, is now worth over $300M CAD in replacement value
- John argues the incoming Colombian president, whom Iacono has known for 25 years, will grant the permits Denarius needs
- John notes he toured Denarius's Colombia and Spain projects this year, calling Spain a pristine-looking asset bought from a billionaire
A 22-cent EV per ounce on Silver47 Exploration's 246M silver-equivalent ounces screens 2-10x below peers like Blackrock Silver, framing a clear valuation gap. The CEO argues most ounces are inferred, but three high-grade US projects (Red Mountain, Hughes, Mogollon) underpin a 1B-oz aspiration and a 2027 PEA. With $45M Canadian in working capital and four rigs running, Silver47 plans roughly 20,000 meters of 2026 drilling across Alaska, Nevada, and New Mexico. Co-hosts Don Duret and John Fenwick frame a deep correction in US silver developers as a contrarian bottom-fishing setup before a potential second leg up. Near-term producers like 1911 Gold, Denarius, and LaHontan anchor a broader US silver thesis alongside Silver47, all riding a bipartisan critical-mineral policy tailwind.

Summit Royalties – US$50 Million Revolving Credit Facility Sets Up Future Transactions and Growth
Key Highlights
brief- Currently direct-shipping ore at Zancudo, which the guest says has penalized metal payabilities for the royalty holder
- Installing a 1,000 tpd mill that is expected to considerably improve payabilities once commissioned — a change Summit says it will benefit from directly as the royalty holder
Summit Royalties (TSXV: SUM) secured a US$50M revolving credit facility from National Bank of Canada to fund future royalty and stream acquisitions without diluting shareholders. Management plans to target cash-flowing or near-production royalties that fall below larger peers' minimum deal sizes, banking on multiple small accretive deals compounding NAV. Two development-stage assets — Copperstone (a 4% gold stream in Arizona) and Patangi in Brazil — are projected to drive revenue and GEO growth into 2027. Trading around 0.6x NAV means the credit line's all-in cost sits well below the company's implied cost of equity, making funded deals inherently accretive. Four producing royalties — Madsen (West Red Lake), Bombore (Orazone), Zancudo (Daenerys Metals) and Keysbrook (Iwatani) — still carry embedded growth as operators ramp up throughput.
Mineros ($MSA | $MNSAF) CEO on Growth Story, Investments & 2030 Gold Production Goals
Key Highlights
brief- The host says Denarius has commented on and off camera that Colombia's incoming regime change will be good for the country, which he expects will benefit Mineros' team.
Mineros S.A. trades at 0.47 times net asset value (what its mines and cash are worth) despite a tenfold share-price re-rating under Sun Valley control. Sun Valley Investments deployed about $200 million to take control, then doubled silver recovery and lifted gold output 22% through operational fixes. Guidance rose to 240,000 ounces with costs tracking below plan, and the CEO targets 500,000 ounces by 2030 via the Porvenir project and acquisitions. An upsized $175 million buyback and $30 million dividend program return cash, while a strategic gold reserve keeps bullion in company vaults. Analyst Don Durrett argues quality mid-tier gold producers are the sweet spot, and Mineros still offers tenfold upside on his $7,000 gold assumption.
THESE Gold & Silver Stocks a Screaming BUY - 'More Bullish Than Ever': John Feneck and Don Durrett
Key Highlights
detailed- Feneck says the debenture overhang has been the biggest issue Denarius Metals has addressed, and that the company is clearing it this summer rather than next year because it also expects higher gold prices.
- The stock was about 58 cents US when the debenture news was announced and 41 cents US at the time of recording, down from 90 cents earlier in 2026 — Feneck says it has already taken the news on the chin.
- Feneck made two site visits in 2026, one in Colombia and one in Spain, and says Denarius is among the very few companies he has ever visited.
- Denarius is already producing in Colombia and should be producing in Spain within a few months; Feneck expects good news flow by roughly Q1 2027.
- The company plans to uplist its Canadian listing (DMET) to the TSX later in 2026 because it says current liquidity there is inadequate.
Durrett frames the metals selloff as a correction, not the end of the gold bull market, which he says only breaks below $3,000. Both guests attribute the drop since March 1st to the Iran war rather than mine fundamentals, and warn of another seasonal dip this fall. Feneck's development picks include Silverco, Blackrock Silver and Silver 47, each trading far below its spring highs on unchanged plans. Durrett's stock lists split by horizon: quality North American producers for a year, developers for three-to-five-year multi-bagger attempts. Feneck is bullish on tungsten equities despite an 8-9x spot price surge, because China supplies about 80% and no ETF or futures market exists.

Western Star Resources ($WSR | $WSRIF): Building a U.S. Tungsten Platform
Key Highlights
detailed- John Feneck says Denarius is a top-five gold holding for his fund and a turnaround story: the dilutive de-venture overhang completes this month and he expects the stock to reach about $1 US next year.
- He notes the stock fell from 58 to 39 cents US on the de-venture news but held 38-39 support, with 35-36 the next level, and that 35-40% of the de-venture is held by non-sellers, so most of the pain is already absorbed.
- Don Durrett expects the CBOE Canada DMET listing to migrate to the Toronto exchange by Q3-Q4, opening the stock to buyers who cannot trade the current symbol.
- Durrett says the fully funded 5,000 ton-per-day mill under construction will mark a major step up in scale for the company once running.
Tungsten prices have multiplied this year while China controls roughly 80% of supply, drawing US government funding toward domestic producers. Western Star consolidated twelve past-producing tungsten mines into three brownfield (previously mined) packages across Nevada and New Mexico. The Rowland property historically graded 3.38% tungsten, over ten times the national average, with surface sampling running 1-5%. Eagle Point carries a non-compliant (pre-modern standard) USGS resource of 200,000 tons at 0.6% tungsten, exposed at surface and never drilled. With about 46 million shares and a C$15 million market cap, the CEO argues the stock is deeply undervalued against ore value.

Summit Royalties – Acquisition Of Star Royalties Is Complete, Bringing In A Significant Gold Stream
Key Highlights
brief- Drew Clark says Summit holds a 0.5% royalty on the Zancudo mine, which Denarius operates.
- He notes Denarius has been running a small direct-shipping operation there and, as of the interview, planned to announce a roughly 1,000 tpd mill installation in the current quarter.
Summit Royalties closed its acquisition of Star Royalties, adding a 4% gold stream on the Copperstone project in Arizona to a 48-asset portfolio. A stream is an upfront payment plus an ongoing one (here 25% of spot for 4% of gold), giving Summit growth it did not fund. Mining Americas' new PFS (Pre-Feasibility Study — the detailed economics test before a build decision) supports construction, with first gold targeted by mid-2027. A royalty on Jaguar Mining's Pitangui project should start construction this year and ramp up in 2027, pairing with Copperstone for revenue growth. The guest argues Summit trades near 0.65 of net asset value, and closing that discount through research coverage would lower its cost of capital.
Articles
No articles available
Published articles for this company will appear here
Want the full picture on more companies?
Be one of the first.
A room for resource investors taking shape now — independent, spam-free, no hype.