
1911 Gold Corporation logo

1911 Gold Corporation

AUMB

1911 Gold Corporation, together with its subsidiaries, engages in the acquisition, exploration, development, and extraction of precious metals. It primarily explores for gold. The company holds a land package totaling 58,672 hectares within and adjacent to the Archean Rice Lake greenstone belt in Manitoba. It also owns interests in the True North mine and mill complex located in Bissett, Manitoba; and Apex property consisting of 5 mining claims covering an area of approximately 752 hectares located near Snow Lake, Manitoba, as well as in Tully and Denton-Keefer projects located near Timmins, Ontario. The company was formerly known as Havilah Mining Corporation and changed its name to 1911 Gold Corporation in June 2019. 1911 Gold Corporation was incorporated in 2018 and is based in Vancouver, Canada.

Score

—
Updated
—
—

Data Quality

N/A

Market Cap

N/A

Total valuation

Stock Price

N/A

Latest close

Free Cash Flow

N/A

Annual

Financial Position

N/A

Cash position

PEG Ratio

ⓘ

N/A

P/E ÷ growth

Analysis

Subscribe to see the AI Analysis

Score breakdown, criteria, red flags, bull/base/bear scenarios.

Subscribe

Financials

Subscribe to see Financials

Cash flow, balance sheet, valuation metrics, share structure.

Subscribe

Asset Pipeline

Subscribe to see the Asset Pipeline

Jurisdiction exposure, project portfolio, cost structure.

Subscribe

Information

Key Information

Legal Entity

1911 Gold Corporation

Sector

Precious Metal

Founded

July 25, 2018

Reporting Currency

CAD

Contact Phone

604-900-5620

Headquarters Address

666 Burrard Street , Vancouver , BC V6C 2X8 , CA

Identifiers

Commodity Portfolio

AU Gold Primary

Stock Exchanges

AUMB TSXV • CAD
AUMB:CVE
AUMBF OTC • USD
AUMBF:OTCMKTS

Organization

Subscribe to see Organization

Management team and industry partnerships.

Subscribe

Chart

Loading chart...

Interactive chart powered by TradingView. Use the chart tools to analyze price trends.

Videos

Mining Stock Mailbag: Hycroft, Vizsla, K92, Goliath & More | Oct. 5-9, 2026

Mining Stock Mailbag: Hycroft, Vizsla, K92, Goliath & More | Oct. 5-9, 2026

The Deep Dive
3 days ago 20:30

Key Highlights

detailed
  • The host says CEO Sean Heinrichs is hitting milestones restart stories rarely do: the True North shaft and 26 level are dewatered, the ball mill is commissioned, contract miners are on site and test mining starts this fall.
  • Because the mill and permits already exist, the PEA's initial capital is only about CAD 59 million, which the host calls tiny for a 58,000-ounce-a-year mine.
  • He cautions the company is heading toward a restart without a feasibility study, exactly how restarts go sideways, and that test mining is not commercial production, noting previous operator San Gold went broke running the mine without enough drilling.
  • The stock slid from about $1 in April to the mid-70s even with all that progress, though he notes the gold price itself fell from roughly $4,700 to about $4,100 over the same period.
  • He wants the pre-feasibility study and global resource update this half and the second Oremet loan tranche locked in before its December 4 deadline, and admits he is angry at himself for not buying at 10 cents.

Hycroft's large Nevada gold-silver resource comes with a $2.4 billion mill bill against a $2 billion market cap and heavy dilution. 1911 Gold is hitting True North restart milestones for about CAD 59 million in initial capital, but is restarting without a feasibility study. Vizsla Silver's Panucco project is fully funded with permitting progressing, but January's abduction that killed nine workers is the real overhang. K92 Mining's fully funded expansion targets 400,000 ounces, but 2026 guidance of 190,000 to 225,000 means the ramp is still a promise. The host argues US deficits and interest costs make eventual Fed stimulus inevitable, so now is the time to accumulate quality juniors.

Beaver Creek 2026 - Best Stocks

Beaver Creek 2026 - Best Stocks

Don Durrett
9 days ago 38:24

Key Highlights

detailed
  • Durrett argues the roughly $200 million valuation is very cheap on the free cash flow it should generate.
  • The mill is due to start in the fourth quarter, but he expects only about 25,000 ounces in 2026, a disappointing 2027, and a rebound in 2028.
  • He sees a path to a 100,000-ounce Canadian producer - about 50,000 ounces from True North and another 50,000 from a secondary project.
  • He notes insider ownership around 30% and says they are not for sale, while warning the name will take more work to reach his top grade.

Gold at $4,100 anchors his buy-the-dip plan: add again below $4,000, and again below $3,700. His Beaver Creek list holds 37 stocks, all rated as tenbaggers (ten-times-plus targets), with seven winners out of ten as the goal. He grades risk-reward by letter and number; near-term producers screen best, while late-stage projects carry more risk. Discovery Silver and Osisko Gold Group lead his Canadian gold picks, and Silver X's 250 million ounce resource lifted the grade. Low insider ownership makes Andean Silver, Talisker and Avino the likeliest takeover targets on his list.

GOLD POURS BEGIN IN MONTHS | Shaun Heinrichs - 1911 Gold

GOLD POURS BEGIN IN MONTHS | Shaun Heinrichs - 1911 Gold

The Deep Dive
18 days ago 10:29

Key Highlights

detailed
  • First-pour catalyst: 1911 Gold plans to start test mining this fall, run the mill by year-end 2026, and pour first gold in the new year — the guest calls this the central 12-month milestone for shareholders.
  • Ramp-up math: two crews producing ~200 tons/day today, a third crew targeted in H1 2027 (~600 t/d), and a long-run goal of 1,300–1,400 t/day across seven crews; 2027 output aimed at 24,000–26,000 oz with a run rate pushing 50,000–60,000 oz.
  • PEA reset: the BC Securities Commission flagged the original PEA for over-confident wording on firm historical-mine costs, but the underlying economics are unchanged; a revised PEA is already out, an updated mineral resource estimate is targeted within 6–8 weeks (by November 2026), and a further PEA will fold in three new mine-lease discoveries plus the Ogon-Moroccan resource rather than jumping straight to PFS.
  • 2026 drilling scale: ~4,000 m at Gama, >15,000 m of surface drilling around the mine lease, plus ~20,000 m underground, including two high-grade zones (710/711 and L10) that the company has now connected across a previously empty 250 m gap.
  • Execution-led de-risking: management is intentionally producing — not just drilling — to reconcile tons-to-resource, mine dilution and method effectiveness, even though 2027 output will be lumpy rather than steady-state.

1911 Gold plans to restart milling at True North by year-end 2026, with first gold pours in early 2027. Test mining will use two crews producing ~200 tons/day, scaling toward 1,300-1,400 tons/day and 24,000-26,000 ounces in 2027. An updated mineral resource estimate is due within 6-8 weeks (target: November 2026), incorporating three new mine-lease discoveries. BC Securities Commission required a PEA re-issue because original wording read 'feasibility-like'; economics are unchanged. Long-term run-rate target exceeds 50,000 ounces annually as crews scale to seven across four permitted mines.

Aya Gold & Silver ($AYA): From Updated PEA to Development at Boumadine

Aya Gold & Silver ($AYA): From Updated PEA to Development at Boumadine

Investor TV
20 days ago 49:35

Key Highlights

brief
  • Don Durrett cites 1911 Gold as an example of a producer whose valuation should re-rate once it is in production, noting the stock was around 50-55 cents US on the day of recording versus his estimate of roughly $1 US.

Aya's Boumadine PEA shows a $3.5B base-case NPV and 93% IRR on $463M of capex, with no equity dilution needed. An AISC of $1,100/oz in years one to five keeps Boumadine robust even if silver stays in the low $60s. Full permits plus $200M cash and up to $300M in off-take prepayments leave the project fully funded through construction. The guest calls Boumadine the best gold-silver project globally; the analyst host sees 10x potential as Wall Street ignores the build.

Brien Lundin - Gold Sector Rebound: Where’s The M&A, What Characteristics Actually Matter?

Brien Lundin - Gold Sector Rebound: Where’s The M&A, What Characteristics Actually Matter?

The KE Report
24 days ago 24:35

Key Highlights

detailed
  • The guest says 1911 Gold has a big head start with infrastructure and is advancing.
  • The guest notes the stock had a big run that made his portfolio a lot of money, pulled back, and is now resurging.
  • The guest argues the company is just scratching the surface of its extended land position around the True North complex.

Widely expected Fed rate hikes can mark gold bottoms: shorts exit once the hike is a fait accompli, echoing the December 2015 low. Rising bond yields now signal repayment risk, not opportunity, an environment where both rate paths, hiking or cutting, ultimately support gold. M&A is slow because majors hoard cash and buy 9.9 to 19.9 percent strategic stakes instead, gaining optionality without paying full takeover premiums. Juniors now flatten the Lassonde Curve (the value dip during lengthy development), advancing straight into small, high-margin production to fund exploration without dilution. Premier takeover targets combine extraordinary economics, de-risked studies, and remaining exploration upside; featured names include 1911 Gold, Banyan, Delta, Gladiator, Luca, and Meridian.

Emperor Metals ($AUOZ | $EMAUF): Growing Duquesne West & Moving Lac Pelletier Toward Production

Emperor Metals ($AUOZ | $EMAUF): Growing Duquesne West & Moving Lac Pelletier Toward Production

Investor TV
24 days ago 34:03

Key Highlights

brief
  • The host flags 1911 Gold as a buy candidate at under 60 cents as of mid-September 2026, saying it is preparing to go into production.

Emperor Metals CEO John Florek outlines a path to 3-5 million ounces at the Quebec Duquesne West project, with a PEA (preliminary economic assessment) targeted in 2027. Already-permitted Lac Pelletier could produce about 40,000 ounces per year and roughly $200 million in annual revenue at $5,000 gold, acting as a cash-flow bridge. Six nearby underused mills let Emperor skip building its own plant, a savings Florek pegs at $500 million to $1 billion in capex (capital expenditure). Insiders and high-net-worth holders appear to control more than 30% of a 32% public float, signaling tight supply and management alignment. Hosts frame juniors broadly as deep-value buys, expecting a decisive S&P-gold break around S&P 7,000 to reignite the gold leg higher.

Skyline Builders Group ($KAZR): Developing a Large-Scale Tungsten Project in Kazakhstan

Skyline Builders Group ($KAZR): Developing a Large-Scale Tungsten Project in Kazakhstan

Investor TV
about 1 month ago 48:00

Key Highlights

detailed
  • The hosts argue 1911 Gold is mispriced at 60 cents US and should trade near $1, given its planned Q4 2026 production restart at a past-producing Canadian mine where, by their math, ASIC sits under $2,500 and gold is around $4,500.
  • John applies his Canada free-cashflow-multiple rule (an 8X FCF/market-cap floor) to 1911 and concludes the floor is roughly $1/share — calling the current price 'kind of ridiculous' versus anticipated FCF.
  • Don confirms 1911 is on his list and sizes it as a core holding, agreeing with John that the market is not pricing the imminent production restart.

Skyline Builders Group (KAZR) plans a 50+ year tungsten mine in Kazakhstan targeting 2030 production, with backing from US EXIM and DFC. The project targets 12,000 metric tons of tungsten annually — roughly 15% of current global supply — at cash costs under $100 per MTU. China, Russia, and North Korea control about 87% of global tungsten, creating structural demand for non-Chinese sources used in defense and semiconductors. Management expects US offtake agreements and debt to cover the ~$1.1 billion capex without shareholder dilution, with an MOU already in place. Rotterdam tungsten prices trade at a premium to Chinese prices, signaling Chinese export restrictions rather than a balanced soft market.

What’s Next for Gold & Silver? Market Analysis With Don Durrett and John Feneck

What’s Next for Gold & Silver? Market Analysis With Don Durrett and John Feneck

Investor TV
about 2 months ago

Key Highlights

detailed
  • The guest lists 1911 Gold as #1 on his 'Low Hanging Fruit' Seeking Alpha piece and says it goes into production in Q4.
  • He highlights a secondary-deposit MRE of 700,000 oz at 8 g/t as 'all free' — not in the current valuation.
  • He argues the existing True North mine alone is worth more than the company's current market cap, before any credit for the secondary deposit.
  • He treats it as a near-term producer with embedded ounces the market hasn't priced.

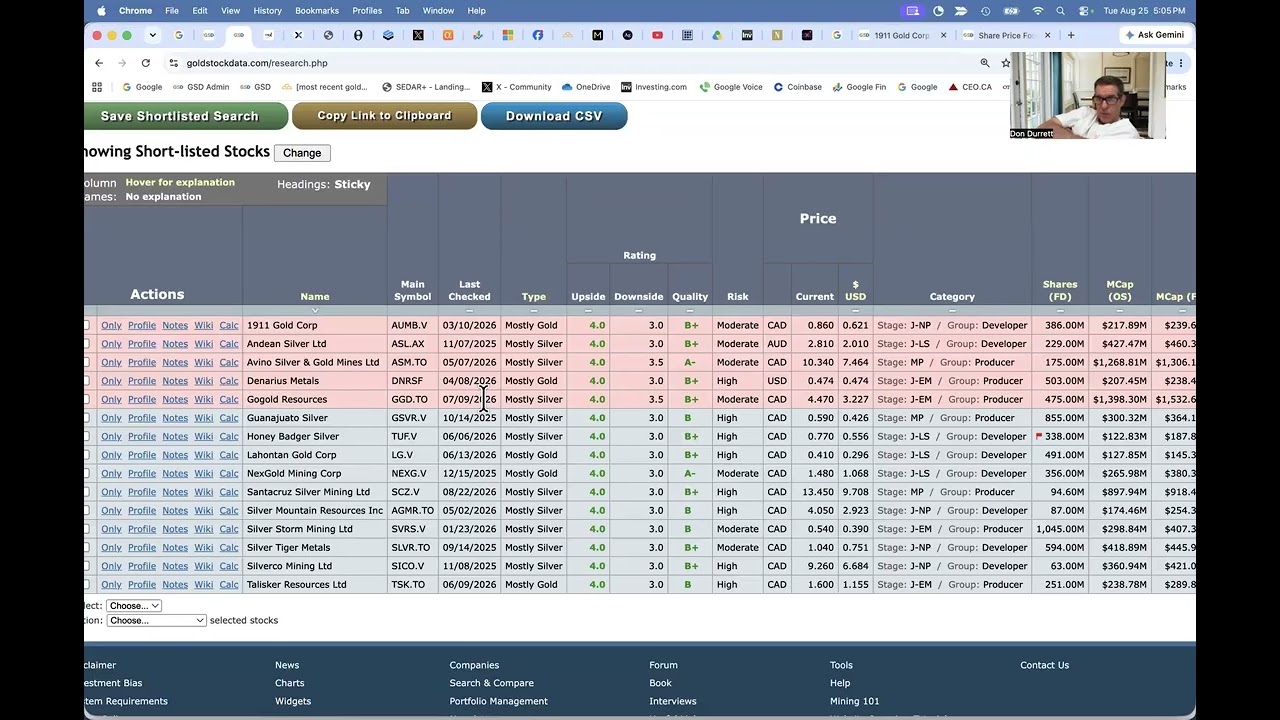
Don and John call the Aug 19 gold-silver rally seasonal, not yet a structural breakout; HUI is above 800. Bessent's surprise long-end Treasury bid weakened the dollar and sent GDX up 8% and silver up 10%. Miners are starting to outperform the metal — a leading signal that institutional rotation into the sector could be starting. Undervalued producers with growth ahead — Goldgroup, Excellon, Denarius, LaHontan, 1911 Gold — screen as the best risk-reward in this tape. Both analysts are bullish into Q4 2026 and 2027, but the real test is whether capital rotates from equities into miners.

Gold/Silver Miners: Low Hanging Fruit (August 2026)

Gold/Silver Miners: Low Hanging Fruit (August 2026)

Don Durrett
about 2 months ago

Key Highlights

detailed
  • Trading at 62 cents with a ~$239M market cap, 1911 is going into production in Q4 of the recording year and ramping through Q1 — he sees a potential 5–7 bagger within ~18 months if AISC stays around $2,500.
  • He models ~45K oz out of the gate with a second ~700K oz deposit to grow toward 75K oz and beyond.
  • The two key risks he names are cost (could print higher than modeled) and grade at the Gilbert area, though he expects grade to hold because the area has been mined historically.
  • He argues 1911 commands a 'location premium' because single-asset Canadian gold producers are scarce — he lists Hemlo, Artemis, Wesdome, New Found Gold, West Red Lake Gold, Blue Lagoon, Talisker, and NexGold as the near-term set.

Don Durrett's 15 low-hanging-fruit names share a single thesis — execution on planned growth at $200 silver and $7,000 gold unlocks 5-20x upside across the list. Junior miners with low insider ownership become prime hostile takeover targets once their assets are de-risked, so a defensive merger often precedes the rerate. The market is still leaving the second-mine pipeline at NexGold and GoGold free, because the first project's standalone value already exceeds today's market cap. Canada's scarcity of new single-asset gold producers gives each one a permanent jurisdiction premium that U.S. peers cannot replicate. AISC (All-In Sustaining Cost — what it really costs to produce an ounce) is the single variable that decides whether each near-term producer on this list rerates or fades.

Share Price Forecast Tool (August 2026)

Share Price Forecast Tool (August 2026)

Don Durrett
about 2 months ago

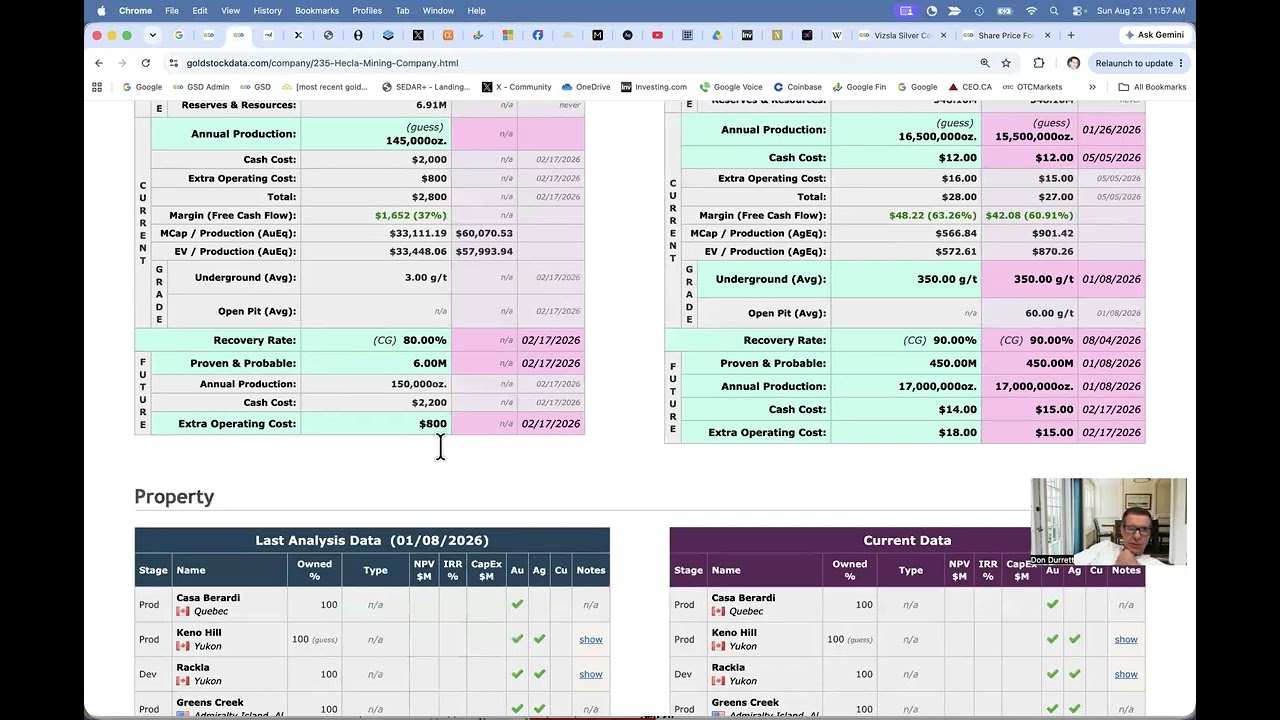
A share price forecast tool turns production, share count, cost, and silver price assumptions into 12-month and three-year return scenarios for miners. Durrett models Hecla at roughly a double in 12 months near $110 silver, and a four- to five-bagger at $200 silver in three years. Developer Vizsla Silver prints the biggest scenarios: a 30-bagger at $200 silver and 40-bagger at $250 silver, with $480 million cash limiting dilution. AISC (all-in sustaining cost — what it fully costs to produce an ounce) and the price-to-cash-flow multiple are the main levers besides metal price. He adjusts developer share counts for expected dilution and capex (upfront capital spending), and expects producer buybacks to shrink share counts.

Goldgroup Mining ($GORO): Building a Multi-Asset Gold and Silver Producer

Goldgroup Mining ($GORO): Building a Multi-Asset Gold and Silver Producer

Investor TV
about 2 months ago

Key Highlights

detailed
  • TOP: Don argues the stock at under US$1 is 'unbelievably cheap' given that the True North mine in Manitoba is on track to go into production this year.
  • The Rockland-Ogama deposit was upgraded from 350,000 ounces to 700,000 ounces at 8 g/t (versus roughly 3.5-4 g/t at True North), which Don expects to add around 50,000 ounces on top of the starter mine.
  • Carries very little debt and is positioned to start generating cash flow once production begins, which Don sees as the catalyst when sentiment finally turns.

Goldgroup's $15M acquisition of Gold Resource Corp added the Don David silver-gold mine, transforming a single-asset producer into a multi-asset Mexican platform. A 26,000-meter drill program at San Francisco targets resource expansion; restart capital is roughly $25M with a target output of about 50,000 ounces a year. Goldgroup is advancing the Back 40 copper-gold project in Michigan but cites an 18-month permitting risk in a Democratic-leaning state. Eric Sprott, Cala, and other insiders control roughly 70% of the float, sharply limiting the risk of a lowball takeover. Forced Russell 2000 selling after a 15-day inclusion window wiped out half the market cap — a mechanical dip that disciplined investors exploited.

Masterclass: Investing In Gold/Silver Mining Stocks (Part 2)

Masterclass: Investing In Gold/Silver Mining Stocks (Part 2)

Don Durrett
2 months ago

Key Highlights

brief
  • The guest says he added to 1911 Gold at about US$0.48, arguing it was heavily discounted and should trade nearer US$1.

Portfolio risk is managed through a pyramid that gives larger allocations to bullion, ETFs, majors, and mid-tier producers. Don Durrett favors mid-tier producers for their balance sheets, free cash flow, and capacity to grow through acquisitions. Allocation should decline as company risk rises, with developers and explorers receiving smaller positions than established producers. Long-term investors should avoid over-trading, buy corrections rather than rallies, and sell when a company’s underlying story changes. Exit decisions should combine valuation, operating performance, targets, and market froth instead of harvesting winners too early.

Gold & Silver Miners, Macro Risks, and Investing Strategy | Don Durrett and John Feneck

Gold & Silver Miners, Macro Risks, and Investing Strategy | Don Durrett and John Feneck

Investor TV
2 months ago

Key Highlights

detailed
  • 1911 Gold is entering production in Q4 with phase-one target ~45,000 oz/year, scalable to 60,000-70,000 oz by adding a 500,000 oz deposit and potentially 80,000-100,000 oz longer-term.
  • Don's math shows that at $6,000 gold (vs ~$4,000 at the time of recording) with a 10x multiple, 1911 prints as roughly a five-bagger over 18 months.
  • John spoke with CEO Sean, who confirmed execution is on track despite a June financing hiccup.
  • At 43-44 cents US, the speakers describe 1911 as 'crazy cheap'.

Don Durrett calls junior gold and silver miners a once-in-a-generation asymmetric trade — entry prices vanish once gold crosses $5,500–$6,000. He values juniors on a 36-month forward gold/silver price ($7,000 and $200 today) instead of spot, capturing leverage before the metal moves. Build a portfolio pyramid — ETFs and majors form the foundation, junior miners sit on top with capped position sizes near 1% of capital. When the original thesis survives a 40% drawdown, add to the position — averaging down improves blended cost basis and removes emotion. The macro case rests on Fed intervention history from Greenspan through today and ongoing de-dollarization — both push investors into gold.

Silver47 Exploration ($AGA | $AAGAF) on Red Mountain's Critical Mineral Potential & Path to 2027 PEA

Silver47 Exploration ($AGA | $AAGAF) on Red Mountain's Critical Mineral Potential & Path to 2027 PEA

Investor TV
2 months ago

Key Highlights

detailed
  • John argues 1911 Gold is a very undervalued gold stock entering production Q4 2025
  • John notes 1911 recently completed a raise and is in a good cash position
  • John says 1911's stock has fallen from $1 to 42-43 cents US, a typical pattern as companies near production
  • Don confirms 1911 enters production Q4 2025 and ramps through Q1 2026

A 22-cent EV per ounce on Silver47 Exploration's 246M silver-equivalent ounces screens 2-10x below peers like Blackrock Silver, framing a clear valuation gap. The CEO argues most ounces are inferred, but three high-grade US projects (Red Mountain, Hughes, Mogollon) underpin a 1B-oz aspiration and a 2027 PEA. With $45M Canadian in working capital and four rigs running, Silver47 plans roughly 20,000 meters of 2026 drilling across Alaska, Nevada, and New Mexico. Co-hosts Don Duret and John Fenwick frame a deep correction in US silver developers as a contrarian bottom-fishing setup before a potential second leg up. Near-term producers like 1911 Gold, Denarius, and LaHontan anchor a broader US silver thesis alongside Silver47, all riding a bipartisan critical-mineral policy tailwind.

GoGold Resources ($GGD | $GLGDF): CEO Bradley Langille on Building the Los Ricos Property in Mexico

GoGold Resources ($GGD | $GLGDF): CEO Bradley Langille on Building the Los Ricos Property in Mexico

Investor TV
3 months ago

Key Highlights

brief
  • John flags 1911 Gold as a heavily sold-off Canadian name down from $1.13 to $0.46 despite a recent financing, with both him and Don bullish on the team and a Q4 production start.

Los Ricos South targets first pour in 2028, fully funded with $284M cash against $227M capex and no major equity raise. At roughly $12/oz AISC — what it really costs to produce an ounce — Los Ricos South sits in the top decile of global silver developers. CEO Bradley Langille plans parallel tracks: Los Ricos South into production by 2028, Los Ricos North from PEA to permit by Q1 next year. Langille expects Mexico's open-pit permitting to accelerate under President Scheinbaum, who is methodically clearing the inherited backlog of about 100 operational permits. The Parral operating mine plus copper and zinc byproduct sales generate roughly $60M/yr free cashflow to internally fund Los Ricos development.

50 buy-the-dip stocks (July 17, 2026)

50 buy-the-dip stocks (July 17, 2026)

Don Durrett
3 months ago

Key Highlights

detailed
  • The speaker calls 1911 Gold one of his top picks and expects it to enter production in Q4 2026, saying it has an excellent risk/reward ratio.
  • He notes roughly $200M of market cap against initial production of only about 45,000 oz, and says the payoff needs a second deposit lifting output toward 75,000 oz over a couple of years.
  • It sits in the green, top-25 tier of his 50-stock list, where he says he sees no B-minus grades on either downside or quality.

He reviews 50 gold and silver mining stocks he owns, sizing the upside against $7,000 gold and $200 silver. Most of the list screens as an eight-bagger or better, and he favors undervalued producers growing output. Development names need patience: permits plus roughly two-year builds push many payoffs to 2028 and beyond. He cautions that gold and silver mining stocks are speculative, so keep allocations small and only risk what you can lose.

THESE Gold & Silver Stocks a Screaming BUY - 'More Bullish Than Ever': John Feneck and Don Durrett

THESE Gold & Silver Stocks a Screaming BUY - 'More Bullish Than Ever': John Feneck and Don Durrett

Commodity Culture
3 months ago

Key Highlights

brief
  • Durrett says 1911 Gold is going into production in Q4 2026 in Canada and lists it among his three gold developer choices.

Durrett frames the metals selloff as a correction, not the end of the gold bull market, which he says only breaks below $3,000. Both guests attribute the drop since March 1st to the Iran war rather than mine fundamentals, and warn of another seasonal dip this fall. Feneck's development picks include Silverco, Blackrock Silver and Silver 47, each trading far below its spring highs on unchanged plans. Durrett's stock lists split by horizon: quality North American producers for a year, developers for three-to-five-year multi-bagger attempts. Feneck is bullish on tungsten equities despite an 8-9x spot price surge, because China supplies about 80% and no ETF or futures market exists.

Western Star Resources ($WSR | $WSRIF): Building a U.S. Tungsten Platform

Western Star Resources ($WSR | $WSRIF): Building a U.S. Tungsten Platform

Investor TV
3 months ago

Key Highlights

detailed
  • Don Durrett, who owns it, argues True North offers steady growth: a Q4 2026 production start at about 45,000 oz next year from a 1 million oz deposit, a roughly 500,000 oz phase-two deposit, and a path to 70,000-90,000 oz per year.
  • He says free cash flow at 70,000 oz and $7,000 gold would make the economics a thing of beauty, and that investors are missing the exploration upside across the large property.
  • The host says the stock has been underwater after an early-June financing was pulled and redone later that month, raising about $30 million.

Tungsten prices have multiplied this year while China controls roughly 80% of supply, drawing US government funding toward domestic producers. Western Star consolidated twelve past-producing tungsten mines into three brownfield (previously mined) packages across Nevada and New Mexico. The Rowland property historically graded 3.38% tungsten, over ten times the national average, with surface sampling running 1-5%. Eagle Point carries a non-compliant (pre-modern standard) USGS resource of 200,000 tons at 0.6% tungsten, exposed at surface and never drilled. With about 46 million shares and a C$15 million market cap, the CEO argues the stock is deeply undervalued against ore value.

This is Exactly How 1911 Gold Is De-Risking Its Path to Production

This is Exactly How 1911 Gold Is De-Risking Its Path to Production

CEO.CA
4 months ago 4:35

Key Highlights

detailed
  • The CEO says 1911 Gold is on track for test-mining production toward the end of 2026 and a full restart of production in 2027, with rehabilitation of parts of the underground mine already advancing in parallel.
  • A major mineral resource update is expected by Q4 2026, which the CEO says will show more ounces, a longer mine life, and higher grade, to be followed by the definitive mine plan in early 2027.
  • The CEO argues the company's edge over Rice Lake peers is fully permitted, already-built infrastructure plus a 62,000-hectare land package holding four mines in a permitted mine lease area and multiple unexplored past producers within about 45 minutes' trucking of the central mill.
  • Three new near-mine structures within 300 meters of current workings can be reached with minimal development, which the CEO says could expand production capacity and the resource quickly, and the drilled Algoma Rockland satellite is set to be the first near-mine source fed to the mill.
  • The main hurdles are people and equipment, which the CEO says are being managed through steady local hiring under a technical team working with Eric Vignette and flexible sourcing of rental or used equipment.

1911 Gold lines up steady catalysts — ongoing drill results, test mining by end-2026 — before a full production restart in 2027 from permitted, fully built infrastructure. An expanded Mineral Resource Estimate (MRE — the tally of mineable ounces) lands in Q4 2026, with the definitive mine plan to follow in early 2027. The CEO argues the differentiator is permitted, fully built infrastructure plus a 62,000-hectare land package holding past-producing mines within 45 minutes' trucking of the mill. Three structures within 300 meters of current workings and the Algoma Rockland satellite could lift production quickly, since miners access them without ramping from surface. The binding constraint is people, not geology — the CEO says hiring skilled local staff across geology, engineering, and operations remains a constant scramble.

This Gold Restart Story Could Be Moving Faster Than Expected | Shaun Heinrichs -  1911

This Gold Restart Story Could Be Moving Faster Than Expected | Shaun Heinrichs - 1911

The Deep Dive
5 months ago

1911 Gold is accelerating its restart strategy, prioritizing rapid cash flow generation over the original PEA timeline to capitalize on strong gold margins. The company is targeting early production in 2026 and full production by 2027, with a key resource update expected later this year. Management is actively optimizing grade control and assessing funding options to bring its Manitoba mill and underground operations back online.

Articles

1911 Gold Is Hitting Its Restart Milestones — but the Feasibility Study Is Still Missing

On The Deep Dive's Oct. 5–9, 2026 Mining Stock Mailbag, host Steve Hyland says 1911 Gold (AUMB) is doing what restart stories rarely do — hitting its milestones, with test mining at True North starting this fall. He still wants a pre-feasibility study, an updated global resource, and a second loan tranche locked in before December 4.

3 days ago
Mining Stock Mailbag: Hycroft, Vizsla, K92, Goliath & More | Oct. 5-9, 2026
Read article

Want the full picture on more companies?

Be one of the first.

A room for resource investors taking shape now — independent, spam-free, no hype.

Join the founding community on Discord