Artemis Gold Inc logo

Artemis Gold Inc

ARTG

Artemis Gold Inc., a gold development company, focuses on the identification, acquisition, and development of gold properties. The company's asset portfolio includes a 32.3% equity interests in Velocity Minerals Ltd. that focuses on acquiring, exploring, and evaluating mineral resource properties in Bulgaria. It also holds interest in the Blackwater Gold Project located in central British Columbia. Artemis Gold Inc. was incorporated in 2019 and is headquartered in Vancouver, Canada.

Score

—
Updated
—
—

Data Quality

N/A

Market Cap

N/A

Total valuation

Stock Price

N/A

Latest close

Free Cash Flow

N/A

Annual

Financial Position

N/A

Cash position

PEG Ratio

ⓘ

N/A

P/E ÷ growth

Analysis

Subscribe to see the AI Analysis

Score breakdown, criteria, red flags, bull/base/bear scenarios.

Subscribe

Financials

Subscribe to see Financials

Cash flow, balance sheet, valuation metrics, share structure.

Subscribe

Asset Pipeline

Subscribe to see the Asset Pipeline

Jurisdiction exposure, project portfolio, cost structure.

Subscribe

Information

Key Information

Legal Entity

Artemis Gold Inc

Sector

Precious Metal

Founded

October 2, 2019

Employees

439

Reporting Currency

CAD

Contact Phone

604 558 1107

Headquarters Address

595 Burrard Street , Vancouver , BC V7X 1L3 , CA

Identifiers

Commodity Portfolio

AU Gold Primary
AG Silver Byproduct

Stock Exchanges

ARTG TSXV • CAD
ARTG:CVE
ARGTF OTC • USD
ARGTF:OTCMKTS

Organization

Subscribe to see Organization

Management team and industry partnerships.

Subscribe

Chart

Loading chart...

Interactive chart powered by TradingView. Use the chart tools to analyze price trends.

Videos

Dave Erfle - Gold & Gold Stocks: Beaver Creek Recap, Metals Technicals, Recent M&A

Dave Erfle - Gold & Gold Stocks: Beaver Creek Recap, Metals Technicals, Recent M&A

The KE Report
13 days ago 19:04

Key Highlights

detailed
  • Erfle calls Artemis's takeover of Vista Gold a take-under: about $37 an ounce for 10.5 million in-ground ounces at Mount Todd, well below peers.
  • The deal landed the Monday before Beaver Creek opened, and Vista still held roughly $50 million in cash, he notes.
  • He reads Steven Dean's motive as buying another hard-rock project on the cheap for Artemis to spin off if a buyer ever comes for Blackwater.
  • He expects the takeover wave to continue because producers have repaired balance sheets and must replace ounces mined out.

Beaver Creek was record-busy and juniors arrived cashed up, increasingly choosing to build projects themselves rather than sell, reshaping takeover dynamics. Seniors have repaired balance sheets, paid down debt and paid dividends, so replacing depleted ounces through M&A becomes the logical next step. Artemis's takeover of Vista Gold values Mount Todd's 10.5 million in-ground ounces near $37 each, a take-under reflecting the deposit's hard-rock difficulty. Gold's pullback may extend toward $3,950-$4,000 support if inflation runs hot and hike odds build, with GDX 85 and GDXJ 110 gaps in play. Erfle screens explorers for district-scale land packages, serially successful management, and projects over 5 million ounces that could attract a major.

Sandy McVey of West Vault Mining Inc. talks to John Kaiser | Metals Investor Forum Sept. 2026

Sandy McVey of West Vault Mining Inc. talks to John Kaiser | Metals Investor Forum Sept. 2026

Metals Investor Forum
14 days ago 17:52

Key Highlights

brief
  • The interviewer names Artemis Gold once, as his precedent for the build-then-M&A exit pattern he is describing for junior miners: “And we look at Artemis with the Blackwater. It built it, the thing that Peter hates. Hates to be done. It's turned out to be enormously successful.” His expectation that a company which built its mine ends up either acquired or aggregating others is the interviewer's prediction, not an established fact about Artemis, and the sentence is repeated in the transcript.
  • No resource, production, cost, ownership, jurisdiction or financial figure is given for Artemis anywhere in the video, and the remark “the thing that Peter hates. Hates to be done.” is the interviewer characterising a preference he attributes to someone else, not a position Artemis has stated.

West Vault's Hasbrouck gold project is permitted and build-ready, but the company is deliberately holding off on construction. Chairman Peter Palmeiro, who says he built a 47% stake near 70 cents Canadian, still controls whether to build or sell. The last capital figure cited is $66 million from the 2023 report, which the guest inflates to about $100 million today. Kaiser values the shares at $7 to $11; the guest blames thin trading, a small float and no news flow for the gap. The guest frames higher gold prices as real price gains, so project economics improve as fast as costs escalate.

A $15 Million Silver Bet: Silver Pony Resources (CSE: PONY, OTC: PONIF)

A $15 Million Silver Bet: Silver Pony Resources (CSE: PONY, OTC: PONIF)

Experts Roundtable
20 days ago 1:43:12

Silver Pony's C$15-million market cap is a low-priced way to trade first drill assays from the underdrilled Lardeau silver district, due early October. Panelists flag selection bias: 3,500 to 12,000 gram-per-ton grab samples — selectively picked rocks — guided drilling, so assay widths matter more than grades. CEO Morgan Good points to about C$1.25 million in Roxmore Resources shares free-trading soon as non-dilutive funding flexibility. Geologist Chris Furey moved the drill 18 kilometers mid-season to Revelstoke after a 455 gram-per-ton surface sample, drilling through fold hinges for architecture. Panelists would buy it personally as a short-term drill-hole trade but won't recommend it, noting the paid presentation, warrants, and thin liquidity.

7 Junior Mining Stocks Our Viewers Asked Us to Review

7 Junior Mining Stocks Our Viewers Asked Us to Review

The Deep Dive
28 days ago 13:40

Key Highlights

brief
  • The host cites Artemis Gold's Blackwater mine (sub-$1,000/oz AISC) as proof low-grade open-pit economics work in the same province as Golden Caribou.
  • Blackwater is referenced as a regional comparable to validate Golden Caribou's continuity-style drill results.

Franco-Nevada's $4.3B cash pile likely points to an accretive royalty acquisition rather than more shareholder returns; Metalla is named as a candidate target. Golden Cariboo keeps posting Cariboo-style drill continuity at a $10M market cap, but no resource estimate yet — Osisko Development is the logical eventual buyer. Excellon's Peru pivot hinges on expansion around the past-producing Mallay mine; share count has quadrupled since 2023, highlighting real dilution risk. Bunker Hill's all-share merger with Silver47 (announced August 21) creates a vehicle that, given time, could absorb Blackrock Silver as the next consolidation step. Oroco's banker-CEO hire signals a transaction playbook: Santo Tomás is being groomed for sale to a major, not built into production.

Nick Campbell: This Could Be The Next Billion Tonne District

Nick Campbell: This Could Be The Next Billion Tonne District

VRIC Media
30 days ago 21:08

Key Highlights

detailed
  • The speaker says he was the sixth employee brought on at Artemis Gold and helped grow the company from about a $400 million market cap to roughly an $8–9 billion market cap by the time he left in March 2023.
  • He joined Artemis because he liked its staged approach to development at the Blackwater project, which he calls a strong way to manage risk and capital exposure when bringing an asset into production.
  • The speaker points to Artemis's acquisition of the Blackwater project from New Gold as the trigger that drew him back to Vancouver and into the company.

A 55,000-metre systematic drill program is finally testing the historic Greenwood Copper-Gold District in BC for scale across three targets. Three main zones — Phoenix South, JD Golden Crown, and Lexington — could together host a billion-tonne district at high grades. Existing roads, rail, power, a permitted mill, and tailings storage save roughly a couple hundred million dollars of development capex. Phoenix is fully funded with $50M cash for a two-year exploration program, giving investors two years of news flow without dilution. First Lexington drill results are expected in October, with Phoenix target results in November — assays take roughly six weeks.

GOLD Just Became a Real Alternative to the Dollar (Here’s Why): Nick Campbell

GOLD Just Became a Real Alternative to the Dollar (Here’s Why): Nick Campbell

Commodity Culture
about 1 month ago 47:26

Key Highlights

brief
  • The guest says he was an early employee at Artemis Gold (around the sixth hire) and that, in his telling, the market cap grew from about $400 million when he joined to roughly $9 billion by the August 2026 interview.

Gold's structural bull case rests on central bank diversification away from the USD, accelerated by the 2022 dollar weaponization. Copper supply stays tight because major mines need roughly 25 years from discovery to production, supporting prices above $6/lb. Phoenix Metals controls the consolidated Greenwood copper-gold district in British Columbia, with bulk-tonnage (large-volume, low-grade) potential of up to a billion tonnes. CEO Nick Campbell's track record spans Silvercrest and Artemis, both of which he helped grow from small-cap juniors to multi-billion-dollar producers. First Lexington drill results are due October 2026, with a PEA (Preliminary Economic Assessment) on the permitted mill targeted for next year.

Willem Middelkoop: The Next Financial Crisis, 'Perfect Storm' For Commodities & Mining Discoveries

Willem Middelkoop: The Next Financial Crisis, 'Perfect Storm' For Commodities & Mining Discoveries

Palisades Gold Radio
about 2 months ago

Key Highlights

brief
  • The guest counts Artemis Gold as one of his fund's successful 'starting producer' bets, grouped with G Mining and Skeena as cases of 100-200% re-rates as new mines come online.
  • Artemis Gold is cited as a 'did well' example in his side pocket of producers transitioning into production.

Weimar lite is already underway as foreign holders have dropped below 30% of US Treasuries and the Fed has absorbed $330B in a year. Central banks have bought around 1,000 tonnes of gold per year for five straight years -- about a third of global mine output. Gold is being reintroduced into the monetary system without any formal conference, as central banks now hold more gold than Treasuries. Gold producers print record free cash flow at PE ratios of 10-11, roughly a tenth of Magnificent Seven valuations. Discovery investors hold at least 1% stakes in tier-one deposits, scaling back after runs but never selling through production.

Rio2: Condestable Expansion Approved, Fenix on Track for 100koz in 2027

Rio2: Condestable Expansion Approved, Fenix on Track for 100koz in 2027

Mining Network
about 2 months ago

Key Highlights

brief
  • Cited by the guest as a model after a roughly $450M CAD debt restructuring with National Bank about six months before the interview

Super El Nino disrupted Fenix Gold first-year heap-leach ramp-up, prompting Rio2 to pull 2026 gold guidance rather than chase unattainable numbers. Wheaton gold prepay (95,000 oz over 7 years) is Rio2 main balance-sheet drag - they plan to retire it via senior debt once AISC hits ~$2,000/oz. Condestable copper mine (EIA-approved expansion to 10,000 tpd, FID targeted H2 2026, sub-$50M capex) adds a steady-state cash engine to a one-asset junior. Fenix targets 20,000 tpd throughput and ~100,000 oz by 2027 at AISC ~$2,000/oz - the spread against todays gold price drives meaningful free cash flow. Alex Black long-term vision is a lean, three-mine LatAm gold-copper producer - small Lima team and no Canadian HQ make Rio2 an attractive eventual takeover target.

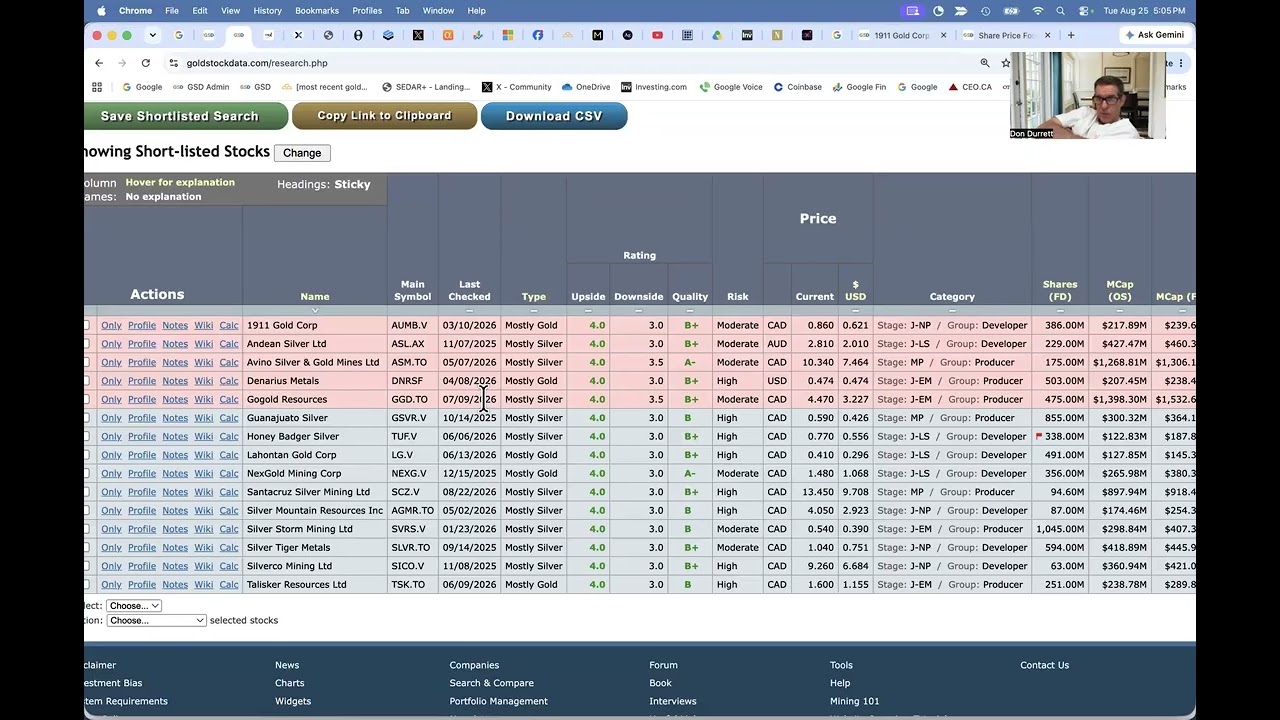
Gold/Silver Miners: Low Hanging Fruit (August 2026)

Gold/Silver Miners: Low Hanging Fruit (August 2026)

Don Durrett
about 2 months ago

Don Durrett's 15 low-hanging-fruit names share a single thesis — execution on planned growth at $200 silver and $7,000 gold unlocks 5-20x upside across the list. Junior miners with low insider ownership become prime hostile takeover targets once their assets are de-risked, so a defensive merger often precedes the rerate. The market is still leaving the second-mine pipeline at NexGold and GoGold free, because the first project's standalone value already exceeds today's market cap. Canada's scarcity of new single-asset gold producers gives each one a permanent jurisdiction premium that U.S. peers cannot replicate. AISC (All-In Sustaining Cost — what it really costs to produce an ounce) is the single variable that decides whether each near-term producer on this list rerates or fades.

How Economic Geologist Neil Adshead Evaluates Early-Stage Junior Mining Stocks

How Economic Geologist Neil Adshead Evaluates Early-Stage Junior Mining Stocks

MiningStockEducation.com
about 2 months ago

Key Highlights

brief
  • The guest points to Artemis's Blackwater mine in BC as evidence the province is open for business — on track, per the speaker, to become a 400,000 ounce/year gold mine and one of the biggest in Canada.

Economic geologist Neil Adshead argues great exploration geologists follow and clearly communicate a disciplined exploration process. Adshead says junior miners need workflow 'hooks' in JV deals so the earn-in partner cannot warehouse the project. For billion-dollar copper capex projects, Adshead says payback period — not headline capex — drives acquirer and investor interest. Adshead flags useful external infrastructure (water, power, roads, town access) as disproportionately important for lower-grade base metals. On portfolio discipline, Adshead urges investors to pause new buying for a month after a big win so emotions can fade.

Independence Gold Hits Three New Gold Discoveries With More Assays Pending

Independence Gold Hits Three New Gold Discoveries With More Assays Pending

CEO.CA
2 months ago 7:20

Independence Gold's 10,000-metre spring program found three new gold-silver veins at 3Ts, with at least 10 major structures still untested. The Balrog, Goofy and Dixie veins sit under at least 30 metres of glacial till that conventional exploration would not have flagged. Base metals hit at depth on Dixie suggest the deposit runs past surface gold and silver, which the CEO calls epithermal-style mineralization. Scaling from roughly 750,000 ounces toward one million gold-equivalent ounces is what draws neighbour and mid-tier company interest. A large assay batch lands between late August and September, feeding a late-fall drill program built partly on new AI-generated targets.

5.65 g/t Gold at Surface: GoldInxs Prepares to Drill at Fishpot Project in BC

5.65 g/t Gold at Surface: GoldInxs Prepares to Drill at Fishpot Project in BC

CEO.CA
3 months ago 5:06

Key Highlights

brief
  • Artemis Gold's Blackwater deposit and mine are cited as the nearby major play, with the guest placing the mine about 65 kilometres from the GoldInxs flagship and using it as an example of a demonstrated successful project in a proven mining district.
  • Blackwater is used as a geological reference point only: the guest is careful to say Fishpot is not a project like Blackwater, even though both share epithermal character, similar volcanic rocks and geochemical signatures.

A maiden 2,000-metre drill program at GoldInxs' Fishpot project is the newly listed explorer's next major test. Airborne geophysics, geological mapping and geochemical sampling have each flagged the same drill targets at Fishpot. Surface rock samples returned up to 5.6 g/t gold, 11.3 g/t silver and copper mineralization ahead of any drilling. The guest calls Fishpot a large epithermal system, citing similar volcanic rocks and geochemistry to Artemis Gold's Blackwater mine, 65 km away. Millar adds Golden Triangle exposure and diversification in a district that has produced Brucejack, SK Creek and KSM.

Mineros ($MSA | $MNSAF) CEO on Growth Story, Investments & 2030 Gold Production Goals

Mineros ($MSA | $MNSAF) CEO on Growth Story, Investments & 2030 Gold Production Goals

Investor TV
3 months ago

Key Highlights

brief
  • Don Durrett names Artemis one of only three Canadian mid-tier gold producers to buy at these levels, noting it entered production in 2024.

Mineros S.A. trades at 0.47 times net asset value (what its mines and cash are worth) despite a tenfold share-price re-rating under Sun Valley control. Sun Valley Investments deployed about $200 million to take control, then doubled silver recovery and lifted gold output 22% through operational fixes. Guidance rose to 240,000 ounces with costs tracking below plan, and the CEO targets 500,000 ounces by 2030 via the Porvenir project and acquisitions. An upsized $175 million buyback and $30 million dividend program return cash, while a strategic gold reserve keeps bullion in company vaults. Analyst Don Durrett argues quality mid-tier gold producers are the sweet spot, and Mineros still offers tenfold upside on his $7,000 gold assumption.

Western Star Resources ($WSR | $WSRIF): Building a U.S. Tungsten Platform

Western Star Resources ($WSR | $WSRIF): Building a U.S. Tungsten Platform

Investor TV
3 months ago

Key Highlights

brief
  • Don Durrett names Artemis Gold, which he owns, among the few standalone single-asset Canadian gold producers, saying he likes it a lot.

Tungsten prices have multiplied this year while China controls roughly 80% of supply, drawing US government funding toward domestic producers. Western Star consolidated twelve past-producing tungsten mines into three brownfield (previously mined) packages across Nevada and New Mexico. The Rowland property historically graded 3.38% tungsten, over ten times the national average, with surface sampling running 1-5%. Eagle Point carries a non-compliant (pre-modern standard) USGS resource of 200,000 tons at 0.6% tungsten, exposed at surface and never drilled. With about 46 million shares and a C$15 million market cap, the CEO argues the stock is deeply undervalued against ore value.

David Lotan Shows You How to Make Junior Mining Millions: Aurion & Fox River Buyouts Explained

David Lotan Shows You How to Make Junior Mining Millions: Aurion & Fox River Buyouts Explained

MiningStockEducation.com
3 months ago

Key Highlights

brief
  • Lotan says Artemis went up 6 or 7 times during the Aurion-Rupert conflict period, far outperforming both quarrelling companies.

Guest David Lotan built most of his Aurion and Fox River stakes buying public shares, arguing open-market bargains beat private deal access. Aurion Resources sold to Agnico Eagle Mines for C$481 million ($2.60 per share cash); Fox River Resources followed at C$94 million ($1.10 per share). Lotan ties the decade-long wait to consolidation among major gold producers; rising mid-tier buying power finally revived takeovers of juniors. The multiyear Aurion-Rupert standoff shows embarrassed, hostile bidders can drag out timelines and destroy value on both sides of a takeover fight. Management teams that refuse warrants (rights to buy future shares cheaply) and protect capital structures earn the investor trust that pays off at exit.

Is Iron Ore the Next Metal to Go Ballistic? 'Price Increase is Inevitable'

Is Iron Ore the Next Metal to Go Ballistic? 'Price Increase is Inevitable'

Commodity Culture
3 months ago

Key Highlights

detailed
  • The guest calls Artemis a success story: its Blackwater project in central British Columbia was built on time, and its planned expansion would make it the second- or third-biggest gold mine in Canada.
  • He says Artemis has gone from roughly $30 million in value when he was involved to somewhere close to $8 billion as of the interview (June 30, 2026).
  • Batalha worked on Artemis with Steven Dean before leaving about two years ago to lead Oceanic; Ryan Beattie, now Oceanic's largest shareholder, held about 30% of Artemis.

Steelmaking's shift to higher-grade feedstock is creating a structural premium for high-purity iron ore, which few jurisdictions can supply at scale. New supply such as the Simandou project mainly offsets depletion at existing mines, so the guest expects only a short-term price dip. Buyers increasingly favor minerals from allied jurisdictions, and Oceanic's tidewater access in Quebec lets it skip costly rail and compete on cost. Oceanic Iron Ore has restarted Hopes Advance after 12 years, with a $50 million raise funding a PFS (Pre-Feasibility Study) due in the fourth quarter. Management argues the stock is undervalued at a 0.1 multiple to NAV (net asset value), with roughly 60% insider ownership backing the restart.

The World Is Running Out of Iron Ore — This Company Has The Answer

The World Is Running Out of Iron Ore — This Company Has The Answer

VRIC Media
3 months ago

Key Highlights

brief
  • The host notes Steven Dean built Artemis Gold into an $8 billion company before turning to Oceanic Iron Ore.

Steel demand is shifting toward high-purity iron ore as green-steel pressure grows and major producers mine out high-grade deposits. Transportation is at least half the all-in cost of iron ore, so tidewater access without rail can decide project economics. Direct reduction iron needs about 67% iron content and under 3% silica (impurities that can make steel brittle), a bar few deposits meet. Iron ore prices anchor to a benchmark 62% grade, then add premiums for higher purity and deduct shipping to the customer. The featured Quebec project pairs tidewater access with a 1.4 billion tonne resource and a pre-feasibility study (an updated economic study) due late 2026.

Gold Stock Valuation Tips for a “Generational Opportunity” - Analyst Ron Stewart

Gold Stock Valuation Tips for a “Generational Opportunity” - Analyst Ron Stewart

MiningStockEducation.com
4 months ago

Key Highlights

brief
  • Stewart, who does not cover the company, names Artemis as a recent example of exceptional share-price performance from completing the developer-to-producer transition, his evidence for the roughly 300-400% LaSonde-curve value lift.

Low AISC (all-in sustaining cost — what it really costs to produce an ounce) producers offer the safest margins as costs compound about 7% yearly. The guest sees the pullback as a generational gold opportunity and urges homework now rather than backing up the truck amid Middle East volatility. Quality mine builders are scarce, so juniors nearing FID (final investment decision) often sell rather than build, making people the top investment criterion. Clean producer balance sheets and wide valuation gaps set up an M&A wave, with acquirers using NAV premiums to buy developers cheaply. Copper demand looks secure long term on electrification, and the guest cites a 3 to 400% value lift crossing into production.

Don Durrett & John Feneck Interview Mayfair Gold ($MFG | $MINE) on Building a Mine in Ontario

Don Durrett & John Feneck Interview Mayfair Gold ($MFG | $MINE) on Building a Mine in Ontario

Investor TV
6 months ago

Key Highlights

brief
  • Nick Campbell says the biggest share-price revaluation he has witnessed comes from getting a project into free cash flow, a lesson he took from his time at Artemis Gold after leaving SilverCrest.
  • He also credits Artemis with teaching him how much team quality matters in moving a staged asset into production, a lesson he applied when hiring at Mayfair.

Mayfair Gold is permitting a 4,800 tonne-per-day starter pit at Fenn-Gib provincially, cutting years off the federal route to first production. Projects under 5,000 tonnes per day permit provincially in Ontario, avoiding a federal review where no new (greenfield) mine has won approval since 2019. Management guides to a sub-$1,200 AISC (All-In Sustaining Cost — the full cost to produce an ounce) and first gold in 2030. Staying small preserves optionality: regional high-grade and underground tonnes can sweeten mill feed (raise average grade) without expanding throughput or new federal permits. Don Durrett favors undervalued, leveraged silver producers while John Fenwick argues war headlines, not fundamentals, gate gold's next move.

Independence Gold is Chasing 1M Ounces with Expansion Drilling at the 3Ts Project

Independence Gold is Chasing 1M Ounces with Expansion Drilling at the 3Ts Project

CEO.CA
6 months ago 7:21

Key Highlights

brief
  • The host notes Independence Gold sits about 160 km from Artemis Gold's Blackwater mine, and Turner says the access road runs right past the operating Blackwater site — a year-round graded road that gives the 3Ts project easy accessibility.
  • Turner describes a good working relationship with Artemis as neighbors, having cooperated in the past on practical issues ranging from forest fires to fuel.

Independence Gold launched a 10,000-metre drill program at 3Ts, aiming to grow its 765,000-ounce resource toward one million gold-equivalent ounces. A 2025 resource update moved half the ounces into the indicated category (supported by enough drilling confidence for planning) for the first time. Newly discovered Johnny, Ian and Larry veins, plus the untested Dobby target running 18 grams, are expected to add ounces. New five-year permits unlock 250 drill targets over the main zone and 75 pads to the east, removing past drilling restrictions. Proximity to Artemis Gold's Blackwater mine, which is already mining, gives 3Ts year-round graded road access most isolated juniors lack.

Articles

Want the full picture on more companies?

Be one of the first.

A room for resource investors taking shape now — independent, spam-free, no hype.

Join the founding community on Discord