Andean Precious Metals Corp
APMAndean Precious Metals Corp. engages in the acquisition, exploration, development, and processing of mineral resource properties in the United States. The company primarily explores for silver and gold deposits. It holds 100% interest in San Bartolomé project in Bolivia; and the Soledad Mountain mine and heap leach located in Kern County, California. The company was incorporated in 2018 and is based in Toronto, Canada. Andean Precious Metals Corp. operates as a subsidiary of PMB Partners LP.
Score
—Data Quality
Market Cap
N/A
Total valuation
Stock Price
N/A
Latest close
Free Cash Flow
N/A
Annual
Financial Position
N/A
Cash position
PEG Ratio
ⓘN/A
P/E ÷ growth
Analysis
Subscribe to see the AI Analysis
Score breakdown, criteria, red flags, bull/base/bear scenarios.
SubscribeFinancials
Asset Pipeline
Subscribe to see the Asset Pipeline
Jurisdiction exposure, project portfolio, cost structure.
SubscribeInformation
Key Information
Legal Entity
Andean Precious Metals Corp
Sector
Precious Metal
Founded
December 31, 2024
Employees
501
Reporting Currency
CAD
Contact Phone
437-371-2820
Website
andeanpm.comHeadquarters Address
181 Bay Street , Toronto , ON M5J 2T3 , CA
Identifiers
ISIN
CA03349X1015Commodity Portfolio
Stock Exchanges
Organization
Chart
Interactive chart powered by TradingView. Use the chart tools to analyze price trends.
Videos
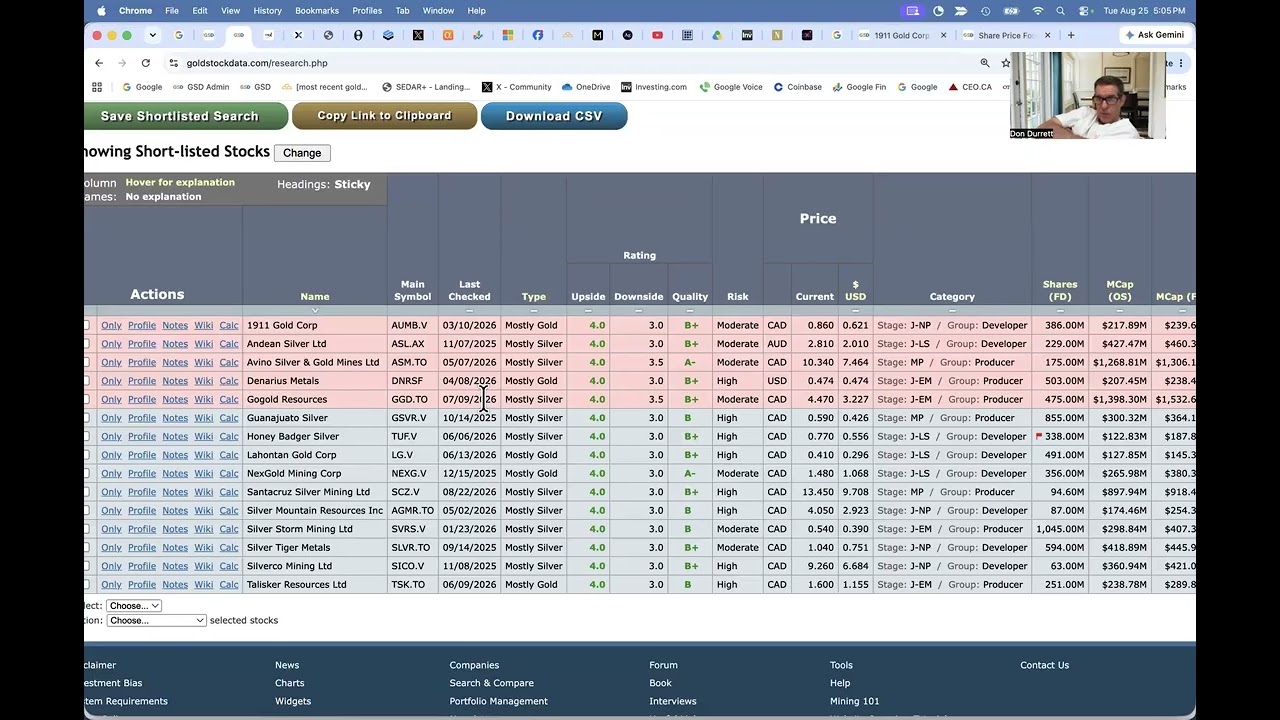
Gold/Silver Miners: Low Hanging Fruit (August 2026)
Key Highlights
detailed- At a ~$420M market cap, the guest expects Andean to start producing 5M oz of silver in H1 2028, potentially expanding toward 7M oz, on a ~100M oz deposit with exploration upside.
- He flags Andean as a likely takeover target because it is cheap, on care-and-maintenance with low capex, yet no hostile bid has appeared — he says he's 'shocked' and 'still waiting for one'.
- The main red flag he names is weak insider ownership, which he says leaves the company exposed to a hostile approach.
Don Durrett's 15 low-hanging-fruit names share a single thesis — execution on planned growth at $200 silver and $7,000 gold unlocks 5-20x upside across the list. Junior miners with low insider ownership become prime hostile takeover targets once their assets are de-risked, so a defensive merger often precedes the rerate. The market is still leaving the second-mine pipeline at NexGold and GoGold free, because the first project's standalone value already exceeds today's market cap. Canada's scarcity of new single-asset gold producers gives each one a permanent jurisdiction premium that U.S. peers cannot replicate. AISC (All-In Sustaining Cost — what it really costs to produce an ounce) is the single variable that decides whether each near-term producer on this list rerates or fades.

Live Q&A with Rick Rule, hosted by Steve Barton 📱
Rick Rule argues resource equities remain reasonably priced after two years of gains, but a 2008-style liquidity crisis could force overexposed investors to sell. Consolidation keeps rewarding shareholders: mergers cut duplicated overhead, and larger miners gain index inclusion, passive buying, and a lower cost of capital. Oil's move from $65 to $105 is anticipatory pricing for rationing, so an unresolved conflict points to higher energy prices ahead. Copper holding firm despite oil-driven slowdown and speculator selling defies Rule's expectations, an anomaly he flags without claiming an answer. In the Q&A, Rule calls Cameco's flood a buying opportunity, favors debt-free Uranium Energy, and explains net present value's blind spots on tier-one deposits.

Live Q&A with Rick Rule, hosted by Steve Barton
Rule argues resource equities are not excessive despite two years of gains, but liquidity-crisis risk means checking your own exposure. Mining consolidation looks set to continue; Rule favors owning likely takeover beneficiaries because mergers cut overhead and lower capital costs. Rule calls Cameco's flood-driven sell-off a buying opportunity, since a three-month outage barely dents reserves measured in decades. Build NPV (net present value — discounted future cash flow) from measured and indicated resources only, then add back optionality for growth and tail. Development-stage mining assets deserve a basket approach across several names, Rule says, never a single speculative position.

Andean Precious Metals: Gold & Silver Producer in the Americas | JC Sandoval and Jimmy Connor
Key Highlights
detailed- Andean operates two producing, cash-flowing assets — the San Bartolomé silver processing plant in Bolivia and the Golden Queen gold mine in California — and JC Sandoval flags Golden Queen life-of-mine extension as the main near-term catalyst.
- Balance sheet stands at over $160 million in cash and cash equivalents against just $30 million in bank debt, after generating more than $60 million in free cash flow last year, supporting both organic growth and a search for a third asset.
- Golden Queen produces 40,000–50,000 ounces of gold annually at all-in sustaining costs of around $2,000 per ounce, with more than $50 million invested post-acquisition and another $30 million allocated to stabilize production and extend the mine life.
- San Bartolomé runs a third-party ore processing model — roughly 50% spot purchases (35–45% target gross margin) and 50% long-term fixed-price contracts from 15–20 suppliers including state-owned COMIBOL — which JC argues provides a natural hedge against silver-price swings.
- The company is actively pursuing M&A for a third asset in the Americas (Canada, US, Mexico, with some South America), preferring gold or silver exposure and open to copper projects tied to the energy transition.
Andean's two-asset model pairs a 100% third-party ore processing plant in Bolivia with a producing gold mine in California, balancing silver and gold exposure. Blending fixed-price contracts with spot purchases at San Bartolome creates a natural price hedge, keeping margins intact through metal price swings. Golden Queen's AISC sits near $2,000, elevated by heavy equipment reinvestment that should taper as the operation matures. With over $160 million in cash and $30 million of debt, Andean is actively hunting a third Americas-based acquisition, preferring gold, silver, or copper. The near-term catalyst is a year-end 2026 43-101 technical report expected to extend Golden Queen's mine life beyond the current two-year estimate.
Articles
No articles available
Published articles for this company will appear here
Want the full picture on more companies?
Be one of the first.
A room for resource investors taking shape now — independent, spam-free, no hype.